
Blogs
PW Consulting: Global Opto-Isolators Market to Reach $4.89B by 2032 at 5.78% CAGR
By pmarketresearch, 2026-09-17
Strategic Isolation: Navigating the Global Opto-Isolators Market Outlook 2026-2032
The opto-isolator market stands at a critical inflection point. As electronic systems grow increasingly complex and power densities rise across industrial, automotive, and telecommunications infrastructure, the demand for reliable galvanic isolation has transitioned from a design consideration to a strategic imperative. PW Consulting's latest Worldwide Opto-Isolators Market research delivers a comprehensive, data-driven examination of this evolving landscape, providing decision-makers with the analytical rigor required to navigate supply constraints, regulatory shifts, and intensifying competition through the 2032 forecast horizon.
This report is not merely an aggregation of historical figures. It is a forward-looking strategic instrument designed to inform capital allocation, supplier qualification, product roadmap planning, and geographic expansion decisions. By synthesizing granular segmentation analysis with real-time industry dynamics, the study equips engineering leaders, procurement directors, and corporate strategists with actionable intelligence that transcends surface-level market summaries.
Executive Market Trajectory: From Recovery to Sustained Expansion
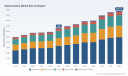
The global opto-isolator market has demonstrated resilient growth over the past half-decade, recovering from early-pandemic supply disruptions and capitalizing on structural demand drivers across multiple end-use sectors. Historical revenue data from 2020 through 2025 reveals a clear upward trajectory, with total market valuation climbing from approximately 2.48 billion USD to 3.30 billion USD. This foundational growth sets the stage for an accelerating forecast period, during which the compound annual growth rate is projected at 5.78 percent through 2032.
By the close of the forecast window, the market is expected to surpass the 4.89 billion USD threshold, reflecting sustained investment in high-voltage power conversion, electric vehicle charging infrastructure, industrial automation networks, and next-generation telecommunications equipment. The pace of expansion will not be uniform across all segments. Certain application verticals and product categories will outpace the broader average, driven by technological substitution, regulatory mandates, and geographic supply chain realignment. Identifying these pockets of disproportionate growth is essential for companies seeking to optimize portfolio exposure and capture margin-enhancing opportunities.
Understanding the magnitude of this expansion requires more than top-line figures. The interplay between substrate availability, component qualification cycles, pricing elasticity, and regional manufacturing capacity will determine which organizations can execute aggressively and which will face margin compression. Our research dissects these variables with precision, enabling stakeholders to model scenario-based outcomes rather than rely on static projections.
Segmentation Dynamics: Where Growth Concentrates and Why
The opto-isolator market is inherently multidimensional. Product architectures, application requirements, and regional manufacturing ecosystems create a complex matrix of demand signals that cannot be adequately captured through aggregated reporting. This study undertakes a rigorous examination of the three primary segmentation axes: type, application, and region.
Type-Level Architecture and Performance Optimization
Across the product taxonomy, distinct performance profiles dictate adoption patterns. High-speed logic gate devices continue to serve as the backbone of digital communication isolation in microcontroller interfaces and factory automation controllers. Transistor output configurations remain heavily utilized in power supply feedback loops, motor drive gating, and inverter control circuits where cost-efficiency and proven reliability intersect. Triac and SCR output variants maintain relevance in AC switching applications, particularly within smart grid infrastructure and appliance-level power management. Linear optocouplers, meanwhile, address precision analog signal transmission requirements in medical instrumentation and sensitive measurement equipment where non-linear distortion must be minimized.
The competitive positioning within each type category is shaped by factors including switching speed, isolation voltage ratings, common-mode transient immunity, package footprint, and long-term thermal stability. Our analysis maps these technical differentiators against volume demand trajectories, revealing where product evolution is outpacing legacy designs and where incremental improvements yield meaningful competitive advantage.
Application Verticals: Driving Structural Demand
End-use application segmentation provides the clearest window into forward demand elasticity. Industrial automation represents a foundational pillar, fueled by the proliferation of programmable logic controllers, robotics integration, and high-density power conversion in manufacturing environments. Automotive and electric vehicle applications are experiencing a structural acceleration, driven by the electrification of powertrains, onboard charger architectures, battery management system isolation requirements, and the gradual adoption of high-voltage traction platforms.
Telecommunications infrastructure continues to demand robust isolation solutions for base station power modules, optical network equipment, and power factor correction circuits. Consumer electronics applications, while more price-sensitive, remain volume-significant, particularly where regulatory standards mandate reinforced insulation for equipment operating above specific voltage thresholds. Medical device applications, though smaller in absolute revenue contribution, exhibit high barriers to entry and stringent qualification requirements that create durable customer relationships and premium pricing environments.
Each application vertical carries distinct qualification timelines, volume volatility profiles, and supply chain dependencies. The report isolates these characteristics to help organizations align production planning, inventory strategies, and engineering resource allocation with the realities of their target markets.
Regional Distribution and Supply Chain Realignment
Geographic demand patterns reflect both historical manufacturing footprints and emerging investment flows. Asia Pacific continues to command the largest share of aggregate revenue, supported by extensive electronics manufacturing capacity, growing domestic automotive production, and expanding industrial infrastructure investment. North America and Europe maintain substantial market presence, driven by high-reliability industrial controls, specialized medical device manufacturing, and advanced telecommunications deployments.
Latin America and the Middle East and Africa represent smaller but evolving demand centers, where infrastructure modernization programs and selective electronics manufacturing initiatives are gradually expanding addressable markets. The regional landscape is further complicated by export control frameworks, localized content requirements, and shifting semiconductor supply chain strategies that influence where components are designed, fabricated, and distributed.
Our geographic analysis moves beyond revenue distribution to examine lead time differentials, regional pricing variances, logistics bottlenecks, and the strategic implications of near-shoring and friend-shoring initiatives. These insights are critical for organizations evaluating warehouse positioning, dual-sourcing strategies, and long-term supplier partnerships.
Competitive Landscape: Ten Key Players Shaping the Market
The opto-isolator market is characterized by a concentrated group of established manufacturers alongside specialized firms that compete on niche performance attributes, qualification depth, and regional service capabilities. Our competitive assessment evaluates the strategic positioning, product portfolio breadth, and recent operational developments of ten companies that collectively exert significant influence over pricing, innovation cadence, and supply availability.
-
Toshiba Electronic Devices & Storage Corporation maintains a broad optocoupler lineup spanning high-speed digital, power, and industrial isolation devices. Its TLP series supports power supply, motor drive, and inverter applications, with recent product sampling activities focused on ultra-compact quad-channel architectures for space-constrained industrial controls.
-
Broadcom Inc. delivers HCPL and ACPL series devices engineered for high-reliability deployments in industrial automation, renewable energy systems, and electric vehicle platforms. The company's recent multi-year supply agreement for gate driver components with a major EV manufacturer underscores the strategic importance of long-term procurement commitments in high-growth verticals.
-
Vishay Intertechnology, Inc. produces VOS and IL series optocouplers, including gate driver and high-voltage isolation products for consumer electronics, telecommunications, and automotive applications. Updated catalog releases expanding temperature operating ranges reflect ongoing efforts to address harsh-environment industrial requirements.
-
Lite-On Technology Corporation offers LTV series digital and analog opto-isolators tailored for power management, medical device integration, and home appliance applications. Its portfolio emphasizes integration flexibility and cost-optimized packaging for high-volume consumer and appliance manufacturing.
-
Everlight Electronics Co., Ltd. supplies EL series components focused on signal transmission in industrial control systems, smart grid infrastructure, and consumer products. Its offerings contribute to broader ecosystem compatibility in applications where standardized interfaces and reliable communication isolation are paramount.
-
ON Semiconductor (onsemi) provides FOD and NCV series devices engineered for automotive, industrial, and safety-critical isolation scenarios. Recent qualification achievements for automotive-grade high-speed components highlight the company's emphasis on meeting rigorous reliability standards in electrified transportation and industrial safety applications.
-
Infineon Technologies AG manufactures optiMOS and EiceDRIVER opto-isolators optimized for gate driving in silicon carbide and gallium nitride power systems, including EV chargers and solar inverter architectures. Its recent launch of a high-isolation opto-driver for SiC MOSFETs demonstrates continued investment in next-generation wide-bandgap ecosystem support.
-
Renesas Electronics Corporation delivers PS and RV series high-speed optocouplers for microcontroller interfaces, factory automation networks, and telecommunications equipment. Its product strategy aligns with the broader industry push toward higher data rates and lower latency in industrial and communication control loops.
-
Sharp Corporation manufactures PC series logic gate and high-output optocouplers serving printer systems, medical equipment, and security infrastructure. Its legacy manufacturing capabilities and specialized output configurations maintain relevance in applications where output drive strength and logic compatibility drive selection decisions.
-
Isocom Components Ltd. specializes in MOC and TLP-compatible optocouplers targeting military, aerospace, and high-reliability industrial environments. Its focus on extended qualification standards and application-specific customization positions it within supply chains where failure tolerance is exceptionally low and long-term component availability is a contractual requirement.
Together, these companies represent a market structure in which the top five participants account for a substantial share of aggregate revenue, while the broader field competes through specialization, regional responsiveness, and targeted qualification wins. Our competitive analysis examines product roadmap alignment, capacity expansion signals, pricing behavior, and partnership dynamics to provide a actionable view of where market share will shift and which capability gaps will create vulnerability.
Industry Dynamics: Constraints, Catalysts, and Structural Shifts
Market growth does not occur in a vacuum. Several concurrent forces are reshaping the opto-isolator supply-demand equilibrium, and understanding their interactions is essential for realistic planning.
Material Availability and Production Economics
Silicon wafer pricing has increased year-over-year due to tightened supply for optocoupler fabrication, directly influencing unit economics and prompting manufacturers to evaluate cost-pass-through strategies, design optimization, and alternative substrate utilization. Simultaneously, lead times for high-common-mode-transient-immunity models have extended into the 20-to-24-week range amid gallium arsenide substrate shortages, creating planning complexity for production scheduling and inventory buffering. Average pricing for 5kVrms digital opto-isolators has also trended upward, reflecting the combined pressure of material constraints, qualification costs, and elevated demand in certain application segments.
Regulatory and Standards Evolution
The IEC 62368-1:2023 standard mandates reinforced insulation for opto-isolators operating above 1kV in consumer electronics, altering compliance requirements for manufacturers and embedding new design constraints into product development cycles. Organizations that proactively align their isolation architectures with these requirements will reduce redesign risk and accelerate time-to-market, while those treating regulatory evolution as a retrospective compliance exercise may face costly late-stage engineering changes.
Geopolitical and Trade Environment
Export control measures associated with the US CHIPS Act have introduced restrictions on advanced opto-isolator technology transfers to China-listed entities, affecting cross-border collaboration, joint development initiatives, and certain supply chain configurations. These measures require companies to reassess technology sharing agreements, distribution partnerships, and manufacturing footprint strategies to ensure compliance while maintaining competitive access to key markets.
Capacity, Qualification, and Strategic Partnerships
Recent corporate developments illustrate how leading manufacturers are responding to these dynamics. Product launches targeting wide-bandgap power systems, expanded temperature ranges for industrial-grade components, automotive qualification achievements, and multi-year supply agreements with major end-users collectively signal a market in which performance differentiation, reliability certification, and supply security are becoming primary competitive differentiators. The organizations that will capture disproportionate value are those that integrate these elements into a coherent strategy rather than treating them as isolated tactical initiatives.
Strategic Imperatives for 2026 Decision-Makers
The convergence of expanding addressable demand, material and lead-time constraints, evolving regulatory standards, and a concentrated yet dynamic competitive field creates both opportunity and risk. Companies that approach the opto-isolator market with fragmented, reactive planning will likely experience margin erosion, qualification delays, and supply disruption. Conversely, organizations that embed comprehensive market intelligence into their strategic planning can achieve several structural advantages.
-
Portfolio Alignment: Matching product architecture investments to the application verticals and type categories with the strongest growth elasticity ensures that engineering resources and manufacturing capacity are deployed where demand momentum is most durable.
-
Supply Chain Resilience: Understanding regional lead-time differentials, substrate availability patterns, and pricing trends enables more accurate inventory modeling, dual-sourcing decisions, and negotiated procurement terms that protect production continuity.
-
Regulatory Anticipation: Proactively designing for reinforced insulation mandates and evolving safety standards reduces redesign exposure, shortens qualification cycles, and positions products for faster market acceptance in regulated end-use environments.
-
Competitive Positioning: Mapping competitor product roadmaps, recent qualification achievements, and supply agreement activity reveals where market share is vulnerable and where differentiation opportunities exist through performance, packaging, or reliability attributes.
Optical Isolators Market -
Geographic Strategy: Aligning distribution, warehouse positioning, and local qualification support with regional demand patterns and trade restrictions allows companies to optimize service levels while maintaining compliance and managing logistics costs.
These imperatives are interconnected. A pricing decision impacts supplier relationships. A qualification timeline affects application entry. A geographic expansion strategy influences compliance exposure. Only by viewing the market through an integrated analytical framework can leadership teams make decisions that compound advantage over time rather than create isolated tactical wins that erode under shifting conditions.
What This Report Delivers
PW Consulting's Worldwide Opto-Isolators Market research is structured to provide precisely this integrated perspective. The study goes beyond headline figures to deliver a multi-layered analysis that supports concrete decision-making across engineering, procurement, sales, and executive functions.
The report includes detailed historical revenue tracking from 2020 through the base year of 2025, establishing a verified baseline against which forecast trajectories can be evaluated. The forward-looking analysis extends through 2032, applying a compound annual growth rate framework that accounts for segment-level variation, regional divergence, and macroeconomic sensitivity.
Segmentation analysis covers product type, application, and region, with revenue distributions and growth pathways examined in relation to technical requirements, qualification cycles, and supply chain realities. Competitive profiling extends across the ten companies identified as market shapers, incorporating product portfolio assessment, recent corporate developments, and strategic positioning analysis that reveals where competitive intensity is rising and where whitespace opportunities persist.
Industry dynamics are treated as active variables rather than static background conditions. Material pricing trends, lead-time extensions, regulatory mandate timelines, and geopolitical trade restrictions are integrated into the analytical narrative to show how they influence pricing, availability, and market entry timing. Recent product launches, qualification achievements, catalog updates, and supply agreements are evaluated not as isolated news items but as indicators of where manufacturers are directing capability investment and how those investments will reshape competitive dynamics.
Market concentration metrics are examined to clarify the balance between incumbent scale advantages and specialist agility, helping organizations assess whether they are competing in a space where volume and qualification depth dominate or where niche performance, regional responsiveness, and application-specific customization drive value capture.
Worldwide Opto-Isolators Market
Accessing the Complete Intelligence
This article provides a structured preview of the strategic terrain covered in the full study. The detailed segmentation revenue distributions, regional growth pathways, application-level demand trajectories, company-level competitive assessments, and scenario-based market projections are developed in depth within the complete report. Those datasets, combined with the analytical framework described here, form the foundation for concrete strategic decisions across product planning, supplier selection, geographic expansion, and capital allocation.
For executives, engineering leaders, and procurement professionals who require precise, actionable intelligence to navigate the opto-isolator market through 2032, the full Worldwide Opto-Isolators Market research from PW Consulting delivers the comprehensive analysis necessary to move from awareness to execution. The complete report, including all segmentation breakdowns, competitive profiles, dynamic factor analysis, and forecast modeling, is available for review on our research portal.
For detailed analysis of this topic, please visit the official page: Worldwide Opto-Isolators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Nursing Call Systems Market to Hit $6.05B by 2032 at 11.72% CAGR
By pmarketresearch, 2026-09-17
Navigating the Future of Healthcare Connectivity: Strategic Intelligence for the Nursing Call Systems Market (2026–2032)
Global healthcare delivery is entering a decisive transformation period, driven by aging demographics, workforce optimization mandates, and the rapid digitization of clinical environments. At the center of this infrastructure evolution lies the nursing call system, a foundational patient-safety network that has evolved from simple wired alert panels into intelligent, interoperable communication hubs. For executives, procurement leaders, and investors navigating capital allocation decisions in 2026, understanding the trajectory of this market is not merely an operational exercise, but a strategic imperative. Our latest Worldwide Nursing Call Systems Market research report provides the analytical framework required to anticipate demand shifts, evaluate competitive positioning, and align technology roadmaps with next-generation care models.
Market Trajectory and Growth Dynamics Through 2032
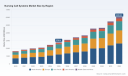
The historical performance of the nursing call systems sector demonstrates consistent upward momentum, reflecting sustained healthcare infrastructure investment and the modernization of aging facility assets. Between 2020 and 2025, the global market expanded from approximately USD 1.65 billion to USD 2.79 billion, underscoring a clear institutional shift toward reliable, scalable communication architectures. Looking ahead, our forecast models project continued expansion through 2032, with the market reaching a multi-billion-dollar valuation as acute care networks, long-term care communities, and outpatient facilities prioritize integrated patient engagement solutions. This growth is anchored by a compound annual growth rate of 11.72 percent over the forecast period, signaling that demand acceleration will outpace broader medical device segments in several regions.
Structural Catalysts Shaping the Forecast
Several converging factors are reinforcing this growth trajectory. Hospital networks are increasingly allocating capital budgets toward patient safety technology, with a measurable reallocation of facility investment toward communication and workflow integration platforms. Simultaneously, regulatory frameworks are tightening interoperability expectations. Compliance with established signaling standards such as UL 1069 remains a baseline requirement for hospital-grade equipment, while wireless deployments in the United States must navigate FDA Class II classification pathways, including 510(k) clearance processes for advanced radio-enabled modules. Beyond device-level compliance, healthcare systems are operating under reimbursement structures that bundle capital expenditures within diagnosis-related group frameworks, meaning that nursing call infrastructure is evaluated through the lens of long-term operational efficiency rather than standalone line-item spend.
Equally significant is the mandate for electronic health record interoperability. The integration of nurse call platforms with clinical data ecosystems using standardized health information exchange protocols is no longer optional for facilities pursuing seamless care coordination. This requirement has accelerated the transition from standalone alert systems to networked communication solutions capable of exchanging context-rich patient data. Together, these regulatory and operational pressures are compressing vendor evaluation cycles and elevating the strategic value of forward-looking procurement planning.
Technology Segmentation and Deployment Realities
The market is structurally divided across technology architectures that serve distinct clinical environments, facility maturity levels, and deployment constraints. IP-based nurse call systems have emerged as the dominant architecture for modern acute care facilities, offering centralized management, scalable network integration, and native compatibility with broader smart hospital initiatives. Wireless nurse call platforms are gaining traction in retrofit projects, senior living environments, and facilities requiring flexible modular expansion without extensive structural rewiring. Wired systems continue to maintain a reliable footprint in new construction and regions where regulatory or infrastructure preferences favor fixed infrastructure. Each architecture carries distinct total cost of ownership profiles, installation timelines, and integration pathways, and the optimal selection depends heavily on facility typology, regional deployment norms, and the desired level of electronic health record connectivity.
End-User Demand Patterns Across Care Settings
Demand is distributed across multiple care delivery environments, each with unique communication requirements and procurement rhythms. Hospitals represent the largest institutional demand center, driven by the need for integrated patient monitoring, staff workflow optimization, and compliance with acute care signaling standards. Nursing homes and assisted living centers constitute a substantial secondary demand segment, where resident safety, fall prevention, and wandering management have become core evaluation criteria for communication platforms. Ambulatory surgical centers and clinics contribute additional demand, particularly in ambulatory care environments seeking lightweight, scalable communication tools that complement rapid patient turnover and modular facility designs.
A critical insight for 2026 decision-makers is that end-user segmentation is not static. As care models shift toward decentralized and hybrid delivery settings, communication platforms originally designed for single-setting deployment are being reevaluated for multi-site interoperability. Facilities are increasingly prioritizing systems that can bridge acute and post-acute workflows, which is reshaping vendor selection criteria and accelerating demand for modular, software-defined architectures.
Competitive Landscape and Strategic Positioning
The vendor landscape is characterized by a mix of established medical device manufacturers, specialized nurse call providers, and communication technology firms expanding into healthcare environments. Market concentration indicators reveal a moderately consolidated competitive structure, with leading participants holding meaningful share while a long tail of regional and niche providers competes on integration capability, service responsiveness, and facility-specific customization. Understanding this competitive architecture is essential for buyers evaluating procurement risk, aftermarket support, and long-term technology roadmaps.
Profiles of Key Market Participants
Rauland remains a recognized provider of Responder nurse call platforms, offering both wireless and wired options with integration pathways for real-time location systems and electronic health records across hospital networks worldwide. Ascom delivers Telligence and smartOne nurse call platforms with DECT and voice-over-Wi-Fi integration, targeting acute care facilities that require robust clinical communication topologies. Baxter, through its Hill-Rom business, markets the Centre Point nurse call system, which emphasizes mobile workflow support and patient monitoring integration across a broad installed base. Stryker, leveraging its Vocera platform, provides wearable badge solutions and nurse call software designed for hands-free clinical communication. TekTone offers nurse call solutions tailored to long-term care and senior living settings, incorporating wander management and reporting capabilities.
Jeron Electronic Systems supplies Pro-Alert and SpectraLink solutions with voice and text messaging capabilities for hospitals and senior living environments. Cornell Communications focuses on nurse call and emergency response systems engineered to meet applicable safety standards for skilled nursing facilities. Alpha Communications provides wireless and entry-point nurse call systems deployed across apartments, hospitals, and assisted living environments globally. Vigil Health specializes in wireless nurse call technology with resident monitoring and fall detection features for senior care communities. Tunstall delivers community care alarm and telecare nurse call solutions with a strong footprint in European and Australian markets. Caretronic develops sensor-based nurse call systems incorporating AI-assisted fall prevention for Nordic and European deployments. Courtney-Thorne provides nurse call systems with DECT telephony integration suited to United Kingdom NHS hospital environments.
Recent Industry Developments Shaping Vendor Momentum
Recent vendor activity highlights the speed at which product roadmaps, regulatory compliance, and commercial contracts are reinforcing competitive positioning. In September 2025, Ascom introduced the myco 4 smartphone with enhanced nurse call interoperability for European hospitals. In June 2025, Stryker secured a multi-year contract for Vocera nurse call deployment across 50 United States hospitals. In March 2025, Baxter updated certification status for its Centre Point nurse call system to support expanded wireless features. In November 2024, Rauland showcased Responder 6 with analytics capabilities at a major international medical trade event. In August 2024, TekTone expanded its catalog with a second-generation wireless module for its MyCall platform.
Worldwide Nursing Call Systems Market
These developments are not isolated product updates; they signal broader strategic shifts toward mobility, interoperability, analytics integration, and expanded wireless validation. For procurement teams, this means that competitive evaluation must look beyond headline specifications and examine vendor capacity to support regulatory evolution, integrated clinical workflows, and post-deployment service reliability.
Strategic Considerations for 2026 Capital and Procurement Planning
As organizations finalize 2026 investment plans, several strategic considerations should guide market engagement. First, interoperability requirements are widening the scope of procurement evaluation. Nurse call systems are increasingly assessed as nodes within a broader clinical communication architecture, meaning that integration readiness with electronic health records, alarm management workflows, and mobile device ecosystems can materially influence total value. Second, facility lifecycle planning is becoming more important than unit-price comparisons. Retrofit constraints, phased deployment capability, and vendor-supported migration pathways can determine whether a solution scales gracefully or becomes a future integration bottleneck.
Decision Levers for Buyers and Investors
-
Evaluate architecture flexibility across IP, wireless, and wired deployment scenarios to ensure alignment with facility modernization timelines and capital constraints.
-
Assess vendor compliance capabilities in relation to signaling standards, wireless device clearance expectations, and interoperability mandates for clinical data exchange.
-
Prioritize platforms that support long-term operational efficiency by integrating patient monitoring workflows, mobile communication tools, and analytics-ready data structures.
-
Examine aftermarket service models, regional deployment support, and training capacity, as these factors frequently determine realized value after installation.
-
Align procurement timelines with broader healthcare capital budgets, recognizing that nurse call upgrades are often bundled within facility-wide patient safety investment initiatives.
Nurse Call Systems Market
Conclusion: Turning Market Intelligence into Forward-Deployed Advantage
The Worldwide Nursing Call Systems Market is entering a period of accelerated structural change, shaped by regulatory modernization, interoperability mandates, wireless adoption, and expanding demand across acute and post-acute care environments. The market expansion projected through the end of the decade reflects more than incremental growth; it signals a broadening definition of what a nurse call system must accomplish within contemporary healthcare delivery. Organizations that approach procurement and investment decisions with a clear view of technology segmentation, competitive dynamics, and regulatory context will be better positioned to capture operational value and reduce implementation risk.
This report is designed to provide the analytical depth necessary to support that decision-making process. It consolidates market sizing, growth trajectory insights, segmentation analysis, competitive profiling, and industry development tracking into a unified strategic framework. To access the full dataset, detailed segmentation breakdowns, comprehensive vendor assessments, and forward-looking scenario analysis, we invite you to explore the complete research publication for the definitive intelligence required to navigate the next phase of healthcare communication infrastructure investment.
For detailed analysis of this topic, please visit the official page: Worldwide Nursing Call Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Opacifying Agent Market to Reach $27,109.83M by 2032 at 4.2% CAGR
By pmarketresearch, 2026-09-17
Strategic Clarity in an Opaque Market: Navigating the Global Opacifying Agent Landscape in 2026
In the complex hierarchy of industrial supply chains, few components are as fundamentally critical yet subtly influential as opacifying agents. While rarely visible to the end consumer, these materials define the aesthetic, functional, and regulatory compliance of products ranging from architectural coatings to personal care formulations. As we move through 2026, the global opacifying agent market stands at a inflection point, characterized by steady growth trajectories, shifting competitive dynamics, and an evolving regulatory environment that demands precise strategic planning.
PW Consulting has released a comprehensive Worldwide Opacifying Agent Market study designed to equip stakeholders with the actionable intelligence needed to navigate this landscape. This article serves as a strategic overview of the market dynamics detailed in our full report, highlighting the macroeconomic trends, competitive maneuvers, and operational challenges that will define decision-making in the coming years. While we provide a high-level view of the market trajectory here, the granular data required for precise capacity planning, sourcing strategies, and investment appraisal is reserved for our complete intelligence suite.
Macroeconomic Trajectory and Market Valuation
Understanding the scale and velocity of the opacifying agent market is the first step in contextualizing investment risks and opportunities. Our analysis covers historical performance from 2020 through the base year of 2025, with forecasts extending out to 2032. This longitudinal view allows organizations to distinguish between cyclical fluctuations and structural growth trends.
Worldwide Opacifying Agent Market
The market has demonstrated resilience and consistent expansion over the past half-decade. Revenue figures have climbed steadily from the 2020 baseline, reflecting sustained demand across core industrial sectors. As we project forward from the 2026 forecast period through 2032, the market is expected to maintain a positive compound annual growth rate. This growth is not merely a function of volume expansion but is also influenced by value optimization across different product types and geographic regions.
Key macroeconomic indicators tracked in the study include:
- Historical Performance (2020-2025): A detailed review of revenue evolution, capturing the impact of post-pandemic recovery and supply chain stabilization.
- Forecast Period (2026-2032): Projected revenue trajectories that account for capacity adjustments, raw material cost volatility, and demand shifts in end-use industries.
- Growth Rate Analysis: Assessment of the CAGR over the forecast horizon, providing a benchmark for potential ROI on capacity expansion or M&A activities.
While the overall market size continues to expand, growth is not uniform across all segments. Our full report dissects these variations without exposing sensitive competitive data, allowing clients to benchmark their own performance against market averages while maintaining strategic confidentiality.
Supply-Side Dynamics and Competitive Landscape
The opacifying agent industry is characterized by a moderately concentrated competitive structure. With a significant portion of market revenue captured by a handful of key players, strategic positioning is critical. The market concentration metrics indicate that while there is room for niche players and regional specialists, the bulk of volume and value is driven by integrated giants with extensive global footprints.
Our study profiles the core entities shaping the market. These companies range from diversified chemical conglomerates to specialized pigment producers. The competitive analysis goes beyond simple revenue rankings; it examines strategic postures, geographic strengths, and technological capabilities.
Key Market Participants Include:
- The Chemours Company: A major global producer known for its Ti-Pure titanium dioxide pigments, serving as a primary opacifying agent across coatings and plastics.
- Tronox Holdings plc: A vertically integrated producer supplying titanium dioxide and feedstock, with a significant presence in paints, coatings, and paper applications.
- KRONOS Worldwide, Inc.: Specializes in titanium dioxide pigments with a strong focus on architectural and industrial coatings, as well as cosmetics.
- LB Group (Lomon Billions): One of the largest Chinese producers of high-performance titanium dioxide pigments, leveraging scale in the Asia Pacific region.
- Venator Materials PLC: A supplier of titanium dioxide and functional additives, actively restructuring its portfolio to focus on core competencies.
- Dow Inc.: Offers ROPAQUE opaque polymers, providing polymeric opacifiers that serve as partial replacements for TiO2 in specific formulations.
- Tayca Corporation: A Japanese producer focusing on titanium dioxide and specialty opacifying materials for industrial and cosmetic uses.
- Evonik Industries AG: Provides specialty chemicals, including zinc oxide-based or hybrid opacifiers for cosmetics and personal care.
- Imerys: Supplies natural mineral-based opacifiers, such as ImerCare Opaque, for gels, shampoos, and personal care products.
- Arkema SA: Offers chemical solutions including opacifiers for coatings, plastics, and various material applications.
The competitive landscape is not static. Recent corporate maneuvers highlight the volatility and strategic recalibration occurring among these leaders. For instance, in early 2026, Tronox Holdings announced the permanent closure of its 46,000-metric-ton Fuzhou TiO₂ plant, citing sulfur feedstock cost escalation and market oversupply. This move underscores the sensitivity of production economics to raw material costs and regional demand balances.
Similarly, portfolio restructuring has been evident among other key players. In late 2025, Venator Materials agreed to divest its UK TiO₂ facility to LB Group, signaling a shift in geographic asset ownership and operational focus. Concurrently, Kronos Worldwide completed the acquisition of Venator's 50% stake in the Louisiana Pigment Company TiO₂ facility, gaining full control over a significant production asset. These transactions illustrate the ongoing consolidation and optimization of supply assets. Furthermore, pricing strategies remain dynamic; The Chemours Company implemented global price increases for TiO2 grades in plastics and coatings segments in late 2025, reflecting the interplay between cost pressures and margin protection.
In our full report, we analyze the market share distribution and competitive positioning of these entities in detail. The specific revenue splits by company and region are critical for understanding vulnerability to supply shocks and pricing power, but these figures are disclosed only to subscribers of the complete study to preserve the integrity of our competitive intelligence.
Segmentation and Application Drivers
The demand for opacifying agents is distributed across a diverse array of industrial and consumer applications. Each segment possesses unique growth drivers, regulatory constraints, and technical requirements. While the overall market grows, the appeal of specific segments varies based on regional industrialization levels and consumer trends.
Primary Application Sectors:
- Paints and Coatings: This remains a dominant consumption hub for opacifiers, driven by infrastructure development, automotive refinishing, and architectural maintenance. The demand here is closely tied to housing markets and industrial construction activities.
- Plastics: Opacifiers are essential for achieving aesthetic standards and UV protection in plastic packaging and automotive components. The shift toward durable and high-performance plastics supports steady demand in this sector.
- Personal Care and Cosmetics: This segment requires high-purity and compliant opacifying agents. Formulations for lotions, creams, and powders rely on specific grades that meet strict safety and regulatory standards.
- Ceramics: Industrial ceramic production utilizes opacifiers to achieve desired visual and physical properties, linked to construction and consumer goods manufacturing.
- Paper and Packaging: Opacity is a critical quality parameter for packaging materials, influencing consumer perception and product protection.
Product Type Dynamics:
The market is also segmented by the type of opacifying agent employed. Titanium Dioxide remains the cornerstone of the industry, valued for its high refractive index and versatility. However, alternative types such as Zircon Silicates and Opaque Polymers are gaining traction in specific applications where TiO2 faces regulatory hurdles or cost disadvantages. For example, polymeric opacifiers are increasingly explored as partial replacements in architectural coatings to manage costs and address specific regulatory concerns regarding TiO2 classification in certain jurisdictions.
Natural mineral-based opacifiers also hold a position, particularly in personal care, where brands seek natural derivative ingredients. The balance between synthetic pigments and natural minerals shifts based on end-user preferences and regulatory frameworks. Our report provides a detailed breakdown of revenue contribution by type and application, allowing clients to identify high-growth niches without exposing the specific market share percentages of competitors in each segment.
Critical Industry Dynamics: Regulation, Raw Materials, and Innovation
Strategic decision-making in 2026 requires a robust understanding of the external forces shaping the market. Regulatory changes and raw material economics are two of the most potent variables influencing supply stability and cost structures.
Regulatory Landscape
The regulatory environment for opacifying agents, particularly titanium dioxide, has been subject to intense scrutiny and evolution. A significant development occurred in August 2025, when the European Court of Justice upheld a ruling that titanium dioxide is no longer classified as a category 2 carcinogen in the EU. This ruling provides regulatory clarity for manufacturers and users within the European market, potentially stabilizing demand that may have been dampened by uncertainty.
However, regulatory complexity persists. Titanium dioxide was added to the Global Automotive Declarable Substance List (GADSL) Reference List on February 1, 2025, triggering reporting thresholds above 0.1% by weight. This affects automotive suppliers and manufacturers who must now adhere to stricter disclosure requirements. Additionally, EU restrictions on titanium dioxide nanoparticles in certain leave-on cosmetics continue to drive reformulation efforts toward compliant opacity systems. These nuances require formulators and procurement teams to stay ahead of compliance curves, a topic covered extensively in our regulatory analysis section.
Raw Material Economics
The cost foundation of opacifying agents is deeply tied to raw material availability and pricing. Ilmenite prices in the USA reached 351 USD/MT in December 2025, reflecting firmer procurement from titanium dioxide producers. This pricing pressure is linked to the ongoing competition among feedstock sources, including ilmenite, leucoxene, rutile, and slag, as reported in the USGS Mineral Commodity Summaries 2026.
Fluctuations in feedstock costs directly impact production margins and pricing strategies for downstream opacifying agents. Companies must navigate these cost volatilities through long-term contracts, vertical integration, or alternative sourcing strategies. Our study incorporates raw material trend analysis to help clients model cost scenarios and hedge against supply chain disruptions.
Worldwide Phosphating Agent Market
Innovation and Reformulation
Beyond regulation and cost, innovation is reshaping the market. The push for sustainable solutions, reduced environmental impact, and enhanced performance is driving R&D in opacifying technologies. From hybrid systems that blend minerals with polymers to specialized grades designed for specific cosmetic textures, innovation is creating new value propositions. Companies like Evonik and Imerys are actively developing specialty solutions that address specific consumer needs while navigating regulatory constraints. Understanding where R&D investments are yielding commercial results is vital for spotting future market leaders.
Strategic Value of the PW Consulting Study
In an environment defined by shifting regulations, raw material volatility, and competitive consolidation, generic market summaries are insufficient for strategic planning. The PW Consulting Worldwide Opacifying Agent Market study offers a depth of analysis tailored for executive decision-makers.
What Our Full Report Delivers:
- Granular Market Sizing: While this overview highlights total market trends, the full report provides specific revenue data for each segment, region, and type, enabling precise market entry or expansion calculations.
- Competitive Intelligence: Detailed profiles of key companies, including their strategic moves, capacity changes, and pricing behaviors, allow for benchmarking and competitive risk assessment.
- Regional Analysis: Breakdown of market performance across Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa, helping identify high-growth regions and localized risks.
- Regulatory Impact Assessment: In-depth analysis of how specific regulations affect different applications and regions, guiding compliance strategies and formulation choices.
- Forecasting Models: Robust forecasting mechanisms that account for various scenarios, providing a range of potential outcomes for 2026 through 2032.
This study is not merely a data repository; it is a strategic tool designed to answer critical questions. Where should capacity be added? Which applications offer the best margin potential? How will regulatory shifts impact supply chains? What are the competitive threats from major players like Chemours or Kronos?
Conclusion: Navigating the Future
The global opacifying agent market presents a landscape of steady growth tempered by complex operational challenges. As the industry moves through 2026, stakeholders must balance the opportunities presented by expanding demand in coatings, plastics, and personal care against the realities of raw material cost pressures and regulatory evolution. The recent strategic moves by major players—ranging from plant closures to acquisitions—signal a market that is optimizing for efficiency and resilience.
For organizations seeking to secure their position in this market, access to precise, forward-looking intelligence is paramount. The PW Consulting Worldwide Opacifying Agent Market study provides the comprehensive data and analysis required to make informed, confident decisions. We invite industry leaders, investors, and strategists to explore the full report for the detailed segmentation data, regional breakdowns, and competitor metrics that will anchor their 2026 strategic planning.
Unlock the full potential of your strategy with deep market intelligence. Access the complete Worldwide Opacifying Agent Market report to secure your competitive edge.
For detailed analysis of this topic, please visit the official page: Worldwide Opacifying Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Radiation-Hardened SSD Market Hits $615.14M in 2025, Projected 11.48% CAGR to 2032
By pmarketresearch, 2026-09-17
Navigating the Radiation-Hardened SSD Market: Strategic Intelligence for the 2026 Decision-Maker
The space economy is no longer a distant frontier; it is a rapidly materializing infrastructure layer that demands resilience at every node. At the heart of this infrastructure lies data storage, and specifically, the radiation-hardened solid-state drive. As commercial constellations multiply and defense architectures evolve, storage solutions must survive ionizing radiation that would cripple conventional enterprise drives. This shift has transformed the rad-hard SSD segment from a niche procurement category into a strategic technology conduit. Our latest market research on the Radiation-Hardened SSD Market provides a structured, decision-grade view of this transition, anchored in historical performance from 2020 through 2025 and extended through a forecast horizon reaching 2032.
The research is designed for leaders who must allocate capital, evaluate suppliers, shape roadmaps, and manage risk in environments where tolerance thresholds, supply continuity, and compliance alignment directly determine mission outcomes. Rather than offering a static snapshot, the report treats the market as a dynamic system shaped by technological substitution, constellation economics, and the growing strain on high-density flash supply. It positions decision-makers to look beyond headline figures and engage with the operational realities that will define competitive advantage over the next several years.
The Market Trajectory: A Signal You Cannot Ignore
What the numbers tell us, in aggregate, is that demand has crossed an inflection point. The overall market expanded from roughly 385 million USD in 2020 to more than 615 million USD in 2025, reflecting a compound trajectory supported by sustained orbital deployment, defense modernization, and scientific research investment. Looking forward, the research models continued expansion through 2032, with medium-term projections indicating a passage into territory approaching the 700 million USD mark in 2026 and sustained upward momentum thereafter as constellation architecture matures and storage requirements become more capacity-intensive.
Behind that trajectory sits a market environment that is both opportunity-rich and structurally constrained. The report translates these dynamics into decision context: where growth is being generated, which technological pathways are gaining share, and where procurement teams should anticipate friction. Rather than presenting fragments in isolation, the analysis integrates technology evolution, application pull, and geographic divergence into a single strategic lens. The result is a framework that helps executives distinguish between cyclical fluctuations and durable structural shifts, particularly as high-density NAND supply faces pricing and lead-time pressure from competing enterprise and AI workloads.
Importantly, the report does not stop at aggregate movement. It examines concentration, technology substitution, and application pull as interconnected forces that shape buyer bargaining power, supplier qualification timelines, and technology roadmap risk. Readers emerge with a clearer sense of where margins are being contested, where standardization is advancing, and where specialized engineering remains the gatekeeper to market entry.
Why 2026 Decisions Require Rad-Hard Intelligence Now
For 2026 planning, timing matters. Program cycles in space and defense are long, qualification processes are rigorous, and supply commitments made today can determine operational readiness years later. The research is structured to support decisions that must be defensible under these constraints. It gives procurement and engineering leaders a basis for evaluating storage options not merely by capacity or footprint, but by radiation tolerance, data integrity architecture, screening alignment, and suitability for mission profiles ranging from low Earth orbit to deep space.
This is especially relevant as constellations scale and storage requirements move toward higher capacities with end-to-end data protection, error mitigation, and robust endurance. The report helps stakeholders assess whether a proposed technology route is aligned with near-term deployment needs or whether it carries hidden risk when exposed to radiation environments, thermal cycling, vibration, and long-duration operation. In practical terms, the analysis supports technology selection, vendor diversification, and roadmap synchronization before commitments become irreversible.
The strategic value also extends to competitive anticipation. As market adoption accelerates, suppliers with differentiated shielding approaches, validated screening practices, and advanced error mitigation are gaining attention, while buyers are increasingly sensitive to capacity availability, qualification lead times, and supply continuity. The research clarifies which capabilities are becoming table stakes and which remain differentiators worth paying for, enabling sharper negotiation positioning and more disciplined sourcing strategies.
Radiation-Hardened SSD Market
What the Report Covers: Operational Depth, Not Just Summary Data
The report is built around actionable content designed for cross-functional use. It moves beyond surface-level sizing to address the operational mechanics that influence purchasing, engineering, and program management. The coverage is organized to make the findings usable in real planning environments, not just as reference material.
Technology Assessment and Substitution Patterns
The analysis examines the major storage technology pathways shaping the market, including single-level cell NAND flash, radiation-tolerant multi-level and triple-level cell NAND, and emerging non-volatile memory approaches such as magnetoresistive RAM and related alternatives. The report evaluates these options in terms of endurance, density, power behavior, data integrity, and fitness for different radiation profiles and mission durations. Technology discussion is connected to practical procurement implications, helping readers understand where legacy architectures remain relevant and where higher-density tolerant memory is shifting the balance.
Application Landscape and Mission Alignment
The research maps demand across space platforms, military and defense systems, and nuclear or scientific research environments. It interprets application pull in terms of operational requirements, not just revenue distribution. Readers gain insight into how storage needs differ by mission class, what data integrity and endurance expectations are implied by each context, and how qualification and screening practices influence procurement readiness. This application framing supports decisions about which solutions are most appropriate for specific program profiles and risk tolerances.
Competitive Landscape and Supplier Positioning
A central element of the report is an assessment of how leading suppliers are competing and differentiating. The analysis examines the strategies of companies including Foremay, Exascend, MEMKOR, Mercury Systems, ATP Electronics, and Flexxon, along with broader ecosystem developments involving component and memory suppliers. The report interprets recent activities within the context of product architecture, radiation-hardening methods, shielding design, endurance claims, and data path protection strategies.
Recent developments are integrated as a way to read strategic direction rather than as isolated announcements. For example, the report contextualizes the March 2026 unveiling of a full InterStellar line of radiation-hardened space-grade NVMe and SATA SSDs with Graded-Z shielding, alongside the November 2025 introduction of a radiation-tolerant space-focused SSD line for low Earth orbit missions, and a July 2025 launch of high-density radiation-tolerant SLC NAND flash for space-qualified portfolios. These events are examined not only for what they reveal about individual companies, but also for what they signal about capacity direction, shielding emphasis, and the expanding range of performance options available to mission planners.
Supply, Screening, and Market Dynamics
The research also addresses the external forces that shape execution risk. It discusses screening practices commonly associated with space-grade components, such as alignment with NASA EEE-INST-002 standards, and outlines how qualification discipline affects reliability and procurement timelines. It further explores the supply-side tension created by competing demand for high-density NAND flash, where enterprise and AI workloads can elevate pricing and extend lead times for specialized storage variants. By placing these factors into the market narrative, the report helps buyers anticipate bottlenecks, evaluate supplier resilience, and plan for longer commitment horizons where appropriate.
Procurement, Qualification, and Roadmap Implications
A distinct section is devoted to turning market intelligence into procurement action. It addresses how to evaluate technology readiness, how to interpret tolerance ratings and shielding approaches in the context of mission environment, and how to manage tradeoffs between performance, capacity, power, and reliability. It also supports roadmap planning by helping organizations compare current offerings against emerging architectural trends, so that selections made today remain aligned with anticipated mission and constellation requirements.
Reading the Competitive Field: Differentiation in a Concentrated Market
Market structure matters because it influences both pricing leverage and technology access. The research notes a concentrated competitive environment, where a relatively small group of suppliers accounts for a substantial share of revenue. This concentration is not simply a statistic; it reflects the specialized nature of rad-hard storage, the importance of qualification heritage, and the technical barriers associated with shielding, error mitigation, and radiation-tolerant memory integration. In such a market, differentiation comes from engineering depth, screening rigor, product breadth, and the ability to match storage architecture to mission conditions.
The report interprets how suppliers are positioning themselves across these dimensions. One theme is the broadening of product lines to span different interfaces and mission classes, from low Earth orbit constellations to deeper space applications. Another is the emphasis on data integrity mechanisms, including end-to-end path protection and error mitigation, which are increasingly valued where continuity matters more than raw density alone. A third theme is the integration of shielding and environmental tolerance as part of the storage solution, not merely an add-on, reflecting the reality that radiation, vibration, and thermal stress must be managed together.
The analysis also examines how component-level innovation influences downstream storage offerings. High-density radiation-tolerant memory releases, for instance, can expand the design space for SSDs and recorders, giving suppliers new options for capacity and endurance while also introducing supply sensitivity. By connecting these layers, the report helps readers understand where supplier advantage may be durable and where it may be vulnerable to substitution or supply disruption.
Decision Levers for 2026 and Beyond
For executives and program leaders, the practical value of the research lies in its ability to sharpen decision leverage. The report supports several recurring planning needs:
Worldwide Rad-hard Semiconductor Market
- Identifying which technology pathways are best aligned with specific mission radiation profiles and duty cycles
- Understanding where higher capacity, endurance, or data protection requirements are reshaping storage selection criteria
- Recognizing supplier strengths and limitations in the context of qualification practices and screening standards
- Evaluating exposure to supply constraints and lead-time variability for specialized flash and rad-hard components
- Anticipating how constellation expansion and defense modernization will shift storage demand over the forecast horizon
- Building sourcing strategies that balance performance, continuity, and qualification risk
These levers are particularly relevant when storage choices interact with broader system design, platform schedules, and program risk tolerances. The report is intended to make those interactions visible, so that storage is treated as an integral part of mission architecture rather than as a commodity component.
How to Use This Research
The report is structured to serve multiple internal audiences. Procurement teams can use it to benchmark supplier offers, qualify technology fit, and anticipate lead-time and availability issues. Engineering leaders can use it to evaluate architectural tradeoffs and map storage requirements to mission profiles. Strategy and business development teams can use it to assess competitive directions, identify partnership opportunities, and frame roadmaps in response to evolving demand. Executives can use it to validate investment timing and resource allocation in a market that is expanding but also becoming more technically demanding.
Because the research integrates market trajectory, segmentation context, technology evolution, competitive activity, and supply-side dynamics, it can serve as a common reference point across functions. That shared baseline is valuable when decisions require alignment between engineering feasibility, procurement realism, and strategic timing.
Access the Full Intelligence
This article provides the strategic context and analytical direction behind the Radiation-Hardened SSD Market research, but it is only the opening of the full intelligence package. The complete report contains the detailed segmentation view, competitive positioning detail, technology pathway interpretation, application-aligned procurement implications, and forecast structure needed to support specific 2026 decisions and beyond.
To obtain the full market size breakdown, segmentation insights, and comprehensive competitive analysis, request the complete research or access the source page where the full dataset and interpretive sections are available. That is where the deeper quantitative detail and supplier-by-supplier strategic assessment can be reviewed in support of your planning objectives.
For detailed analysis of this topic, please visit the official page: Radiation-Hardened SSD Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Card Access Market Hits $13.26B in 2025, Surges at 8.54% CAGR to $23.53B by 2032
By pmarketresearch, 2026-09-17
Strategic Intelligence for the Access Control Enterprise: Why the 2026 Worldwide Card Based Access Control Systems Market Report Matters
The global shift toward integrated physical security, identity management, and operational resilience has placed card-based access control at the center of enterprise infrastructure planning. As organizations reconcile legacy deployments with emerging credential standards, cloud-managed platforms, and tightening regulatory expectations, strategic decision-makers require more than headline growth figures. They need a structured, forward-looking view of demand drivers, technology transitions, competitive positioning, and the operational realities that will shape procurement, integration, and risk mitigation through 2032. Our newly published Worldwide Card Based Access Control Systems Market research is designed for precisely that purpose.
This market research is not a static snapshot. It is a decision-support instrument built to help security directors, IT leaders, facility planners, and corporate strategists evaluate where the market is moving, which segments are gaining traction, and how vendors are repositioning around interoperability, cloud services, and high-assurance credentialing. The report anchors its analysis in a rigorous historical and forecast framework, beginning with a base year of 2025 and extending through 2032. Over the historical review period from 2020 to 2025, the market expanded from approximately USD 8,840 million to roughly USD 13,256 million, reflecting sustained institutional investment in access control modernization across commercial, government, industrial, and institutional environments.
Stadium Access Control System Market
Looking ahead, the forecast period from 2026 to 2032 maps a trajectory of continued expansion. The market is projected to reach about USD 14,363 million in 2026 and climb to approximately USD 23,525 million by 2032, supported by a compound annual growth rate of 8.54 percent. These figures are not presented in isolation. They are contextualized within the operational forces shaping purchase decisions: the migration from legacy proximity formats to multi-technology smart card and contactless credentials, the growing integration of access control with video, intrusion, and building management platforms, and the increasing emphasis on certificate-based security and secure identity workflows. The research translates these forces into actionable intelligence for organizations that must plan budgets, evaluate vendor roadmaps, and align access control investments with broader digital transformation agendas.
Why This Research Is Strategically Relevant in 2026
The 2026 decision environment is defined by a convergence of technology modernization and compliance pressure. Enterprises are no longer asking only whether card-based access control works; they are asking how it fits into an ecosystem of mobile credentials, cloud-managed administration, encrypted communications, and cross-vendor interoperability. At the same time, procurement teams are navigating rising hardware and infrastructure costs linked to broader technology demand cycles, as well as evolving expectations around data sovereignty and on-premises control of credential databases and access logs.
Against this backdrop, the report provides a disciplined framework for interpreting market movement rather than simply documenting it. It helps leadership teams answer questions that directly affect planning cycles: which credential technologies are gaining adoption momentum, how vertical demand differs by security requirement and deployment scale, where regional dynamics are influencing infrastructure choices, and how major vendors are differentiating through platform integration, regulatory alignment, and lifecycle support. By connecting market size and growth patterns to real operational considerations, the research enables more confident capacity planning, vendor evaluation, and long-term investment prioritization.
What the Report Delivers: Operational Depth for Procurement and Planning
The study is structured to support practical use across the enterprise. It combines top-level market quantification with detailed segmentation analysis, competitive profiling, and forward-looking assessment of market dynamics. Readers gain access to a comprehensive view of the market structure, including the principal technology categories, vertical demand patterns, regional distribution of activity, and concentration trends among leading participants.
Worldwide Card Based Access Control Systems Market
Key components of the report include:
- A full historical and forecast revenue analysis that traces market evolution from 2020 through 2032, giving decision-makers a consistent basis for benchmarking growth expectations.
- Segment-level interpretation across card technology types, end-use verticals, and geographic regions, enabling organizations to understand where demand is concentrated and how different deployment contexts influence product and service requirements.
- Competitive landscape analysis that profiles leading manufacturers and platform providers, focusing on their product portfolios, credentialing capabilities, integration strategies, and areas of strategic emphasis.
- Market concentration metrics that clarify the share structure of the industry, helping stakeholders assess competitive intensity and the balance between established platform leaders and specialized solution providers.
- Market dynamics assessment that connects regulatory frameworks, technology standards, infrastructure cost trends, and procurement behavior to the broader trajectory of the market.
Crucially, the report avoids reducing the market to a single number or a generic growth narrative. Instead, it examines how different deployment models, security requirements, and organizational priorities create distinct demand signals. This makes the research particularly valuable for teams evaluating whether to standardize on a specific credential technology, expand into new sites or vertical applications, or reassess their access control architecture in response to changing operational and compliance demands.
Competitive Landscape: Platform Leaders, Credential Specialists, and the Shift Toward Interoperability
The competitive environment in card-based access control is both broad and increasingly layered. Established security hardware manufacturers, building management integrators, and specialized credential and identity providers all compete for enterprise deployments, but they do so with different strategic priorities. Some emphasize multi-technology reader portfolios and migration support. Others focus on high-assurance credentials, government-compliant readers, or cloud-managed administration. A further group extends access control into networked video, intrusion, and unified security platforms.
The report profiles the major companies shaping this landscape, including ASSA ABLOY AB, HID Global, Honeywell International Inc., Johnson Controls International plc, Allegion plc, dormakaba Group, Bosch Security Systems GmbH, Nedap N.V., Suprema Inc., Identiv Inc., Gallagher Group Ltd., Axis Communications AB, SALTO Systems S.L., ZKTeco Co., Ltd., and IDEMIA. Rather than presenting these participants as a simple roster, the research analyzes how their portfolios and recent initiatives reflect broader market directions.
For example, the analysis considers how leading providers are strengthening support for proximity, MIFARE, and multi-technology credentials while also advancing secure identity solutions aligned with government and enterprise requirements. It examines how certain vendors are integrating card-based access with building management, video, and intrusion systems to offer broader facility platforms. It also evaluates how others are differentiating through encrypted communications, high-user-capacity controllers, cloud-managed credential administration, and offline or wireless access models for specialized environments such as hospitality and distributed commercial sites.
Recent product and platform developments reinforce the strategic themes captured in the research. In early 2026, Genetec released new access control capabilities in its Security Center SaaS offering to simplify visitor workflows and support enterprise cloud modernization for card-based credential management. Around the same time, Sentry Interactive introduced an SDK for mass enrollment of PKOC credentials, enabling scalable deployment of interoperable physical and mobile credentials compatible with card-based readers. These moves reflect a market increasingly focused on interoperability, cloud-enabled administration, and flexible credential ecosystems.
Earlier developments also illustrate the pace of platform evolution. In late 2025, Honeywell updated its Pro-Watch platform with expanded cloud management for remote handling of card credentials, access schedules, and alarm events. In early 2025, Allegion launched a new series of RFID card readers with multi-format support for both legacy proximity cards and newer smart card formats, easing system migrations. Meanwhile, Nedap implemented AEOS certificate management and device certificate management, providing end-to-end certificate handling for servers, controllers, and card readers. Together, these initiatives show how competitive differentiation is increasingly tied to lifecycle support, migration ease, and cryptographic assurance rather than hardware alone.
Market Dynamics: Regulation, Standards, Infrastructure Costs, and the Data Sovereignty Question
The report situates market growth within a set of dynamics that are actively reshaping procurement and deployment strategies. One major theme is the role of regulatory and standards-based frameworks in guiding hardware selection and system architecture. Compliance expectations continue to influence government and high-security deployments, where approved reader and credential ecosystems matter significantly. At the same time, critical infrastructure operators face a broader set of considerations around communication pathways and access-related controls, prompting organizations to evaluate not only card readers and credentials but also the networks and management layers that support them.
Another defining dynamic is the emergence of interoperability-oriented credential specifications. Open standards work is expanding the feasibility of cross-vendor credentialing and mobile-compatible access models, reducing dependence on closed ecosystems and giving enterprises more flexibility in phased modernization. This matters because many organizations are simultaneously managing legacy proximity installations and planning future expansions that must accommodate newer smart card and multi-technology environments.
Cost pressure also remains a central operational concern. Recent increases in memory and high-bandwidth memory pricing have raised baseline costs for servers and controllers used in networked card-based access control systems. For enterprises planning large-scale deployments or major platform upgrades, this influences not only hardware budgeting but also the timing and architecture of centralized management infrastructure. The report addresses these pressures directly, helping readers understand how macroeconomic and component-level trends can affect total cost of ownership and deployment sequencing.
Data sovereignty and infrastructure placement considerations add another layer of strategic complexity. Organizations are increasingly weighing the tradeoffs between cloud-managed convenience and localized control of credential databases and access logs. This has prompted a measurable shift among some enterprises toward expanding on-premises storage capacity to mitigate vendor lock-in concerns and meet compliance expectations. The research interprets this trend within the broader market context, showing how infrastructure decisions are becoming inseparable from security policy, risk management, and long-term vendor relationships.
How to Use the Report for 2026 Decision-Making
The value of this research lies in its ability to connect quantitative market structure with qualitative strategic inference. Procurement leaders can use the segmentation analysis to understand which technology and vertical contexts matter most in their operating environment. Security architects can use the competitive and dynamics sections to evaluate vendor differentiation, interoperability options, and compliance alignment. Executive teams can use the forecast framework to test assumptions about growth, investment timing, and the pace of modernization across multiple sites or business units.
Because the report is designed as an intelligence platform rather than a one-time summary, it supports several practical use cases:
- Evaluating whether to prioritize migration from legacy proximity systems to multi-technology or contactless smart card environments.
- Assessing vendor fit based on credentialing capabilities, platform integration, cloud management options, and regulatory alignment.
- Contextualizing infrastructure cost pressures and data sovereignty requirements within long-term deployment planning.
- Benchmarking regional and vertical demand patterns to support expansion, standardization, or diversification strategies.
- Anticipating competitive shifts as interoperability standards, certificate-based security, and cloud-enabled administration become more central to procurement decisions.
Conclusion: Precision Intelligence for a Market in Transition
The worldwide card-based access control market is expanding on a clear trajectory, but its real significance for enterprise decision-makers lies in the changing shape of demand. Growth is increasingly tied to credential modernization, cross-platform integration, secure identity workflows, and the operational realities of cost, compliance, and data control. Our Worldwide Card Based Access Control Systems Market report is built to help leaders navigate that transition with confidence.
The complete research package provides the detailed segmentation analysis, company profiles, concentration metrics, and dynamics assessment needed to move from general awareness to precise planning. For organizations preparing investments, migrations, and vendor strategies for the 2026 to 2032 period, the full report offers the depth required to turn market intelligence into actionable strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Card Based Access Control Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Global Commercial Satellite Customization Service Market to Hit $17.75B by 2032 Growing at 16.03% CAGR
By pmarketresearch, 2026-09-17
Navigating the Orbital Economy: Strategic Intelligence for the Worldwide Commercial Satellite Customization Service Market
The Imperative for Customization in a Crowded Sky
The commercial space sector has matured beyond the era of off-the-shelf solutions. As orbits become more congested and mission requirements more specialized, satellite operators and government agencies increasingly demand tailored architectures that align precisely with their operational objectives. From bespoke payloads for Earth observation to fully configured buses for sovereign communications networks, customization is no longer a premium add-on. It is the baseline expectation for market entry and long-term competitiveness.
Our latest research, the Worldwide Commercial Satellite Customization Service Market study, provides decision-makers with a comprehensive, data-driven view of this rapidly transforming landscape. The report is designed to support enterprise strategy through 2032 and beyond, offering senior leaders a clear understanding of market velocity, structural shifts, competitive positioning, and the regulatory currents that will shape procurement, investment, and partnership decisions.
Market Trajectory: A Growth Story Anchored in Structural Demand
The commercial satellite customization market has demonstrated sustained, multi-year expansion. Historical data from 2020 through 2025 reveals a market that has rebounded from early-cycle volatility and entered an accelerated growth phase. Revenue climbed steadily over this period, reflecting the combined effects of orbit diversification, payload sophistication, and the broader commercialization of space infrastructure. The base-year baseline for 2025 establishes a firm foundation for forward-looking projections, while the forecast window from 2026 to 2032 maps the next phase of market evolution.
Momentum continues into the forecast period, with the market projected to maintain a compound annual growth rate of approximately 16.03 percent through 2032. This growth trajectory is not merely a function of volume. It reflects a deeper transformation in how satellite services are conceived and acquired. Customers are moving away from standardized, one-size-fits-all platforms toward mission-specific configurations that address unique orbital slots, data throughput requirements, latency constraints, and sovereign or defense-grade compliance needs. The forecast period captures the compounding effect of these preferences as commercial, government, and scientific end-users expand their footprint across multiple orbital regimes.
Satellite Control Service Market
Currency-denominated revenue metrics tracked in the study reflect a market in which customization services are becoming a distinct, high-value segment of the broader space economy. The report presents these figures in a way that supports financial modeling, scenario planning, and investment prioritization without reducing a complex ecosystem to oversimplified aggregates.
What the Report Delivers: Actionable Intelligence for Executive Decision-Making
The study is structured around practical utility. It goes beyond headline figures to equip strategy teams, procurement leaders, investors, and market-entry planners with the analytical building blocks needed to make informed decisions. The core components include:
- Historical and forecast revenue modeling spanning 2020 through 2032, with a clear base-year anchor and forward-looking scenarios that support budgeting, capacity planning, and market-entry timing.
- Segment-level analysis across satellite size, end-user categories, and geographic regions, enabling stakeholders to identify where demand concentration is forming and where whitespace opportunities may exist.
- Competitive landscape profiling of the companies defining the customization service market, with an emphasis on each player's value proposition, service scope, and strategic positioning.
- Recent market-moving developments that illustrate how new capabilities, partnerships, and product-line launches are reshaping the pace and direction of market growth.
- Regulatory and spectrum dynamics that influence deployment timelines, cross-border data handling, and the feasibility of commercial constellations in key jurisdictions.
- Concentration and competitive intensity metrics that help readers gauge market maturity, barriers to entry, and the extent of competitive overlap across the leading providers.
The report is designed as a living reference for strategy teams. It can be used to benchmark internal roadmaps against external market signals, evaluate the timing of satellite procurement or service contracts, assess the risk-return profile of new market entry, and build defensible positions in an industry where differentiation increasingly depends on mission-specific engineering and integration capability.
A Competitive Arena Defined by Scale, Specialization, and Speed
The customization service market is populated by a mix of established aerospace primes, specialized integrators, and emerging players focused on rapid, tailored builds. The competitive fabric is shaped by differences in geographic footprint, orbital expertise, payload integration depth, and the ability to deliver across multiple mission classes efficiently.
Large, multi-domain space firms continue to anchor significant portions of the market. Companies such as Airbus Defence and Space, The Boeing Company, Lockheed Martin Space, Northrop Grumman, Thales Alenia Space, Maxar Technologies, Capella Space, Umbra, Azista USA, York Space Systems, and ISISpace Group each bring distinct strengths. Some emphasize full satellite design, manufacturing, and customization for commercial GEO, MEO, and LEO missions, offering tailored payloads, buses, and mission-specific configurations. Others focus on bespoke satellite platforms delivered with custom payloads and configurations for communications and observation uses. Several providers deliver end-to-end custom satellite solutions that span mission-specific design, integration, and testing for commercial customers, while others supply customized satellite buses, payloads, and full systems for communications and Earth observation missions.
Specialization is a recurring theme. Some firms specialize in custom satellite manufacturing and integration for commercial telecom and observation satellites across various orbits. Others concentrate on high-resolution Earth observation platforms and tailored geospatial capabilities, or offer custom satellite and mission solutions that include spacecraft bus customization, payload configuration, and sovereign system builds for commercial and strategic needs. A subset of providers has built its identity around delivering custom SAR satellite solutions through dedicated mission solution lines, including bespoke buses, payloads, constellations, and advanced mission capabilities. There are also players that provide end-to-end custom satellite manufacturing across LEO, GEO, CubeSat, and SmallSat platforms tailored to specific mission requirements, as well as firms that focus on bespoke and configurable satellite platforms for commercial, government, and defense customers with full-stack customization. In parallel, some integrators specialize in small satellite customization, including CubeSat and nanosatellite platforms and mission-specific integrations for commercial applications.
Worldwide Commercial Satellite Customization Service Market
This breadth of capability means that no single profile fits every procurement need. Instead, buyers evaluate providers based on orbit class, payload complexity, schedule pressure, integration depth, and the strategic importance of sovereign or protected data handling. The study maps these distinctions in detail so that readers can align supplier selection with mission architecture and commercial strategy.
Recent Developments That Are Reshaping the Market
Recent developments underscore how quickly the customization service market is evolving. In 2025, a notable breakthrough occurred in AI-enabled custom satellite bus design. A company achieved automated high-fidelity structural design for rapid custom satellite buses, signed its first commercial payload customer, and secured funding. This milestone points to a future in which design automation compresses timelines and lowers the marginal cost of customization, particularly for rapid bus and payload integration.
Another significant move came from a SAR-focused provider that announced a new business line for building fully operational custom SAR satellite solutions, including buses, payloads, constellations, and advanced mission capabilities for governments and corporations. The launch of this mission solutions line expanded the commercial availability of tailored radar-based Earth observation and monitoring capabilities, reflecting demand for mission-ready, rather than merely component-level, offerings.
A separate development highlighted the growing role of component selection within AI-enabled custom satellite bus design platforms aimed at rapid ESPA-class satellite production. A major provider was selected to supply components for an AI-enabled custom satellite bus design platform, reinforcing the trend toward modular, high-throughput production pipelines that still allow mission-specific tailoring. These developments are not isolated events. They are indicators of a market in which speed, automation, and mission-specific integration are becoming competitive differentiators.
Regulatory Currents and the Reality of Orbit Realities
Customization is not only a technical and commercial challenge. It is also shaped by an environment of spectrum access, orbital resource management, and data sovereignty concerns. The International Telecommunication Union continues to coordinate global radiofrequency spectrum and satellite orbit resources, while ongoing pressure on spectrum allocation reflects the high data-rate demands of commercial satellite systems. As customization becomes more prominent, securing appropriate spectrum and orbital slots becomes integral to mission feasibility.
In the United States, spectrum policy developments have introduced additional pipelines intended to support commercial satellite deployments and operations. These policy shifts matter for the timing and scale of commercialization, especially for operators seeking to expand service coverage and throughput through tailored systems. At the same time, national data sovereignty laws and regulations require careful observance in satellite data handling and operations, particularly for cross-border commercial satellite communications and services. Providers and operators that offer customization must account for these compliance dimensions from the outset, not as an afterthought.
On the deployment side, the schedule for LEO constellation build-out remains a closely watched indicator of market timing. Plans for the launch of initial production satellites for a commercial broadband LEO constellation in late 2026 illustrate how infrastructure rollout continues to accelerate and how customization demands may evolve as operational constellations move from design to in-orbit service delivery. Such milestones serve as benchmarks for when customization services will be called upon not only for initial mission builds but also for payload refresh, integration upgrades, and sovereign or commercial capacity expansion.
Concentration, Market Structure, and Strategic Interpretation
The market exhibits a degree of competitive concentration, with the top three and top five providers representing meaningful shares of revenue. This structure suggests that established players with broad integration capabilities and long-standing mission portfolios maintain strong positions, while nimble specialists and automation-driven entrants are creating new value propositions around speed, flexibility, and mission-specific delivery. For customers, this means a dual imperative: leverage the reliability and mission depth of large integrators where appropriate, while evaluating emerging providers for programs that require faster cycle times or highly specialized configurations.
For investors and strategists, concentration metrics offer a lens on competitive intensity and the sustainability of differentiation. A market that balances concentrated leadership with a growing base of specialized entrants creates opportunities for partnership, acquisition, and vertical integration. It also raises questions about supply-chain resilience, payload availability, and the extent to which customization can be scaled without sacrificing mission quality. The report provides the analytical scaffolding needed to interpret these dynamics in relation to specific business cases.
Why This Study Matters for 2026 Decision-Making
Strategic decisions made in 2026 will shape positioning through the end of the decade. The Worldwide Commercial Satellite Customization Service Market study is built to support those decisions by connecting macro trends with actionable detail. It helps leaders answer questions that go beyond market size:
- Where is customization demand most durable across satellite size categories and end-user segments?
- Which providers are best positioned to deliver mission-specific solutions across GEO, MEO, LEO, CubeSat, and SmallSat environments?
- How are AI-enabled design tools and rapid bus integration changing the economics of customization?
- What regulatory and spectrum realities should be factored into market-entry and procurement timelines?
- How should organizations interpret concentration metrics when evaluating competitive risk and partnership opportunities?
By blending historical performance, forward-looking forecasts, recent developments, and sector context, the study provides a decision-grade foundation for investment planning, supplier selection, mission architecture, and market-entry strategy. It is designed to be used by strategy teams who need more than a narrative. They need a structured intelligence resource that links observable market signals to concrete strategic choices.
Access the Full Market Intelligence
The breadth of customization in the commercial satellite market is expanding as fast as the market itself. Tailored payloads, mission-specific buses, sovereign configurations, rapid small satellite integrations, and AI-assisted design workflows are all converging to redefine what is possible in orbit. Understanding where value is being created, by whom, and under what constraints is essential for any organization operating in or adjacent to the space economy.
The full report contains the detailed segmentation, competitive profiles, recent developments, and regulatory context required to move from high-level awareness to precise planning. It is the kind of intelligence that supports confident decisions in a sector where timing, technical specificity, and compliance can determine success or delay. For leaders who need a complete, verified view of the market and its trajectory through 2032, the complete study is available through PW Consulting's research portal. Accessing the full report unlocks the deeper insights and scenario-ready detail that executive teams need to act with clarity in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Commercial Satellite Customization Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Millimeter Filters Market Hits $716.44M in 2025, Projected 10.45% CAGR to $1.44B by 2032
By pmarketresearch, 2026-09-17
Navigating the Decade of Disruption: Strategic Intelligence for the Global Millimeter Filters Market (2026-2032)
The global millimeter wave (mmWave) filter market stands at a critical inflection point. As wireless communication systems migrate to higher frequency bands and defense architectures demand greater spectral purity, the component level has become the bottleneck for system-level performance. PW Consulting's latest research, Worldwide Millimeter Filters Market 2026-2032 , provides a comprehensive strategic framework for stakeholders navigating this high-growth, high-complexity landscape.
Worldwide Millimeter Wave Therapeutic Device Market
Based on historical analysis from 2020 through the base year of 2025, the market has demonstrated robust demand elasticity. The overall market size has evolved from 452.4 million USD in 2020 to an estimated 716.44 million USD in 2025. Looking forward, the forecast period from 2026 to 2032 projects a trajectory of sustained expansion, with the market volume expected to reach 1436.62 million USD by the end of the forecast horizon. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 10.45 percent, signaling a decade where filtering technology will be as strategic as the semiconductor chips they support.
For C-suite executives, supply chain managers, and R&D directors, this report is not merely a collection of statistics. It is a decision-support tool designed to mitigate risk in a supply-constrained environment, identify white spaces in a crowded competitive field, and align product roadmaps with the evolving regulatory and technological realities of the millimeter wave spectrum.
The Macro Picture: Valuation and Growth Vectors
Understanding the velocity of this market is essential for capital allocation. The data indicates that the period between 2025 and 2032 will likely see the market more than double in revenue terms. In 2026 alone, the market is projected to hit 806.74 million USD, bridging the gap between the immediate post-5G rollout phase and the deeper integration of mmWave in automotive and satellite sectors.
However, aggregate numbers only tell part of the story. The true value of this research lies in dissecting the drivers behind the 10.45 percent CAGR. The expansion is not uniform; it is concentrated in specific technological niches where performance requirements are most stringent. The shift from sub-6 GHz deployments to FR2 bands in telecommunications, coupled with the modernization of radar systems for electronic warfare and automotive sensing, creates a compound demand effect.
Investment decisions made in 2026 must account for the continuity of this growth curve. Stakeholders need to evaluate whether their current production capacities or sourcing strategies can sustain participation in a market that grows by approximately 150 to 200 million USD annually over the next half-decade. The report provides the granularity required to model these scenarios without exposing the organization to speculative forecasting errors.
Worldwide Millimeter Filters Market
Market Segmentation: Type, Application, and Geographic Nuances
Technological Segmentation and Demand Priorities
The market is stratified by filter type, each serving distinct signal processing needs. Band Pass Filters currently command the largest share of revenue, reflecting the dominance of selective frequency passing in modern communication chains. Low Pass Filters, High Pass Filters, and Band Stop Filters constitute the remainder of the typology, each addressing specific impedance matching and harmonic suppression requirements.
While specific revenue splits are reserved for the full dataset, the strategic implication is clear: the demand for Band Pass solutions is inextricably linked to the proliferation of broadband wireless standards. Meanwhile, Band Stop Filters are seeing renewed interest in applications where interference mitigation is critical, such as in dense urban electromagnetic environments or within complex radar waveforms. The report details the performance specifications—insertion loss, rejection ratios, and bandwidth capabilities—that are currently defining market winners across these categories.
Application Drivers: From 5G to Electronic Warfare
The application landscape is equally diverse. Telecommunications and 5G Infrastructure represent the primary revenue engine, driven by the need for filters that can handle high frequencies with minimal thermal drift. However, the report highlights a significant secondary vector: Radar and Electronic Warfare. As defense budgets prioritize spectrum awareness and jamming resistance, the demand for high-rejection mmWave filters in this sector is accelerating.
Satellite Communications and Automotive Radar form the emerging growth pillars. The miniaturization of satellite payloads requires filters that are not only high-performing but also exceptionally compact and lightweight. Similarly, the evolution of automotive radar beyond the 77 GHz standard into higher mmWave bands for higher resolution sensing is creating new specification requirements for suppliers. The research analyzes how these application segments interplay, identifying where cross-pollination of technology might occur and where supply chain segregation is necessary.
Regional Dynamics and Supply Chain Realities
Geographically, the market is distributed across Asia Pacific, North America, Europe, and the Rest of World. Each region presents a unique value proposition. Asia Pacific continues to be a hub for volume manufacturing and integration, particularly within the telecommunications supply chain. North America remains a center for high-performance, defense-grade, and custom RF solutions. Europe maintains a strong presence in specialized industrial and aerospace applications.
Crucially, the report examines the supply chain vulnerabilities inherent in this geographic distribution. The concentration of certain raw material sources, specifically regarding Gallium-nitride wafer supply chains, introduces strategic risk for component suppliers. Understanding where these bottlenecks exist allows procurement teams to diversify sourcing or invest in alternative material technologies before disruptions impact production timelines. Furthermore, the report navigates the complex regulatory environment, including export control parameters that affect the transfer of advanced microwave and millimeter wave items between specific country groups, ensuring compliance strategies are aligned with market opportunities.
Competitive Landscape: Profiles and Strategic Movements
The millimeter filter market is characterized by a mix of established RF giants and specialized niche players. The top five companies currently command approximately 58.8 percent of the market revenue, while the top three hold 42.5 percent, indicating a moderately concentrated landscape where differentiation is key to capturing share.
Key Incumbents and Their Strategic Postures
Several core enterprises define the current competitive baseline. Knowles Precision Devices (DLI), based in the United States, offers catalog and custom 5G mmWave filters for FR2 bands including 26 GHz, 28 GHz, and 39 GHz. Their solutions feature 3 GHz bandwidth and greater than 50 dB rejection in surface-mount packages 20x smaller than alternatives, with temperature stability ranging from -55°C to +125°C. This level of miniaturization and stability sets a high bar for commercial cellular applications.
Reactel, Inc., also United States-based, designs and manufactures high-performance RF, microwave, and millimeter wave filters, multiplexers, and multifunction assemblies covering DC to 67 GHz. Their coverage across aerospace, defense, telecommunications, and industrial markets makes them a diversified player capable of bridging commercial and government sectors.
Benchmark Lark Technology provides compact, lightweight surface-mount mmWave bandpass filters using stripline and substrate-integrated waveguide (SIW) designs for 5-40 GHz applications. Their focus on small footprints and temperature-stable performance for 5G, satcom, and defense positions them well for size-constrained platforms.
Mini-Circuits supplies LTCC and thin-film mmWave filters including bandpass for 5G FR2 bands, low pass up to 30+ GHz, and waveguide bandpass up to 86 GHz. Their broad catalog availability supports rapid prototyping and volume production for a wide range of integrators.
Other notable players include Millimetre Wave Products Inc. (MI-Wave), offering waveguide bandpass filters from ~8 GHz to 140 GHz with low insertion loss and high rejection up to 60 dB; Qualwave Inc., a China-based manufacturer emphasizing low insertion loss and high frequency accuracy for 5G and military radar; TERASi from Sweden, developing ultra-compact E-band waveguide filters using AirCore technology that are 40x smaller than conventional alternatives with less than 0.4 dB insertion loss; and Wainwright Instruments GmbH from Germany, specializing in evanescent mode ridge waveguide designs extending into millimeter wave frequencies for mobile and satellite applications.
Recent Developments Shaping the Trajectory
Market dynamics are not static; they are driven by product launches and strategic announcements. In June 2024, Benchmark Lark Technology introduced new families of compact surface-mount XFH Series and STL Series mmWave bandpass filters for 5-40 GHz with small footprints for 5G, satcom, and defense applications at IMS 2024. This move signaled an intensification of competition in the surface-mount segment.
In April 2025, TERASi announced the development of ultra-compact E-band waveguide filters using AirCore technology, achieving packages 40 times smaller than conventional alternatives with less than 0.4 dB insertion loss for 5G radio systems. This innovation highlights the industry's push toward extreme miniaturization without sacrificing performance, a critical trend for dense urban infrastructure and airborne platforms.
More recently, in March 2026, Reactel, Inc. announced exhibition of a full line of application-specific RF, microwave and mmWave filters, multiplexers, and multifunction assemblies up to 67 GHz at IMS 2026 in Boston. Such activity underscores the ongoing investment in R&D and the willingness of incumbents to defend their turf through comprehensive portfolio showcases.
Strategic Imperatives and Risk Factors for 2026 Decision-Makers
As organizations plan their strategies for the remainder of the decade, several imperatives emerge from the data. First, supply chain resilience is non-negotiable. The concentration of Gallium-nitride wafer supply chains introduces strategic risk for component suppliers in millimeter wave technology including filters. Companies must assess their exposure to single-source dependencies and consider long-term agreements or alternative material qualifications.
Second, regulatory compliance is a market access barrier. The U.S. Bureau of Industry and Security (BIS) export controls on certain advanced computing and semiconductor items include parameters for microwave or millimeter wave items under 3A001.b, effective April 2024 with restrictions to specified country groups. For exporters and multinational supply chains, understanding these parameters is essential to avoid legal pitfalls and ensure uninterrupted delivery to key markets.
Third, differentiation through performance is the only sustainable competitive advantage. With a CAGR of 10.45 percent, the market will attract new entrants. Incumbents and new players alike must focus on metrics that matter to system designers: insertion loss, rejection ratios, size, weight, power, and thermal stability. The report details the specific specification thresholds that currently command premium pricing versus those that are becoming commoditized.
Finally, the shift in application mix requires portfolio agility. While telecommunications remains the volume leader, the high-margin opportunities in radar, electronic warfare, and satellite communications are growing rapidly. Companies that can pivot their manufacturing capabilities or forge partnerships to serve these higher-barrier segments will capture disproportionate value relative to the overall market growth rate.
Conclusion: Turning Intelligence into Advantage
The Worldwide Millimeter Filters Market is poised for a transformative decade. The revenue trajectory from 716.44 million USD in 2025 to over 1.4 billion USD by 2032 reflects a fundamental shift in how the world communicates, defends, and navigates. However, realizing the value of this growth requires more than passive observation. It demands precise intelligence regarding segmentation trends, competitive maneuvering, and the regulatory and material constraints that shape the supply chain.
PW Consulting's Worldwide Millimeter Filters Market 2026-2032 delivers this intelligence. It provides the detailed segmentation splits, historical data analysis, company profiles, and forward-looking strategic assessments necessary to make informed decisions. The market is complex, but the path to success is clear for those equipped with the right data. Stakeholders are invited to explore the full report to unlock the specific regional and application-level details that will define their next strategic move.
For detailed analysis of this topic, please visit the official page: Worldwide Millimeter Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Military Laser Market Hits $1,420.5M in 2025, Forecast 10.45% CAGR to 2032
By pmarketresearch, 2026-09-17
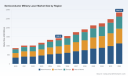
Strategic Horizons: Navigating the Worldwide Semiconductor Military Laser Market in 2026
The defense technology landscape is undergoing a paradigm shift where directed energy is moving from experimental prototypes to operational deployment. At the heart of this transition lies the semiconductor laser, a critical enabler for high-energy weapons, precision targeting, and advanced sensing. PW Consulting latest release, the Worldwide Semiconductor Military Laser Market study, offers a comprehensive blueprint for stakeholders aiming to secure a competitive advantage in this rapidly evolving sector. As organizations finalize their strategies for the 2026 fiscal year, understanding the trajectory of this market is not merely an option; it is a strategic imperative.
This intelligence briefing synthesizes macro-level trends, competitive dynamics, and regulatory pressures to provide a clear view of the opportunities and risks that define the landscape. By examining the convergence of technological advancement, government procurement priorities, and supply chain vulnerabilities, decision-makers can align their portfolios with the forces shaping the future of military photonics. The following analysis outlines the strategic value contained within our latest market research, highlighting why immediate access to granular data is essential for sustained growth.
Macro Growth Trajectory and Revenue Outlook
The financial magnitude of the semiconductor military laser market underscores its significance within the broader defense industrial base. Historical performance from 2020 through 2025 reveals a consistent upward trajectory, driven by intensified global security concerns and the operational advantages of directed energy systems over conventional munitions. Our research indicates that the market has expanded from approximately 875.4 million USD in 2020 to an estimated 1420.5 million USD in 2025.
Looking ahead, the forecast period spanning 2026 to 2032 projects sustained momentum with a compound annual growth rate of 10.45 percent. Revenue projections demonstrate a robust climb, positioning the market to reach significant valuation milestones by the end of the decade. This growth is fueled by multi-year investment commitments from defense departments seeking scalable, cost-effective solutions for counter-drone operations, missile defense, and naval protection. The acceleration reflects a broader doctrinal shift where electronic and directed energy capabilities are integrated into layered defense architectures.
For corporate strategists, this revenue expansion signals more than just aggregate opportunity; it highlights the critical importance of timing. Early movers who align their product development cycles with the projected demand surge will capture disproportionate market share. Conversely, organizations that delay entry or misjudge the pace of adoption risk ceding ground to competitors who are already scaling their manufacturing capabilities and securing long-term supply agreements. Understanding the precise inflection points and the variables that could alter the growth curve requires deep access to the segmentation and scenario modeling provided in our full report.
Segmentation Dynamics and Value Pools
The allocation of market value across different dimensions reveals where the highest concentration of opportunity resides. The market is not monolithic; it is fragmented across technology types, application domains, and geographic regions, each with distinct growth drivers and competitive intensities. Our detailed segmentation analysis dissects these layers, providing the granularity needed to identify target segments that align with specific corporate capabilities and risk appetites.
In terms of technology, the landscape encompasses diode lasers, vertical cavity surface emitting lasers, and edge emitting lasers. Each category serves different performance requirements, ranging from high-efficiency pumping for directed energy subsystems to compact modules for sensing and countermeasures. The value distribution across these types reflects the ongoing trade-offs between power output, beam quality, thermal management, and integration complexity. Companies must evaluate which technological pathway offers the best alignment with their core competencies and the evolving specifications of end-user platforms.
Application-wise, the market spans target designation and range finding, directed energy weapons subsystems, lidar and navigation, and laser countermeasures. These application areas correspond to different procurement cycles, budgetary priorities, and technical hurdles. The demand for directed energy subsystems, for instance, is closely tied to fielding schedules for high-energy laser weapon systems on ground, sea, and air platforms. Meanwhile, countermeasure and sensing applications continue to benefit from the proliferation of asymmetric threats and the need for autonomous defensive capabilities. Understanding the relative weight and interaction of these segments is vital for prioritizing R&D investments and go-to-market strategies.
Competitive Landscape and Strategic Positioning
The rivalry within the semiconductor military laser market is shaped by a mix of major defense primes and specialized photonics firms, each leveraging unique assets to secure their position. Our study profiles leading organizations such as Northrop Grumman Corporation, RTX Corporation including Raytheon, Lockheed Martin Corporation, nLIGHT Inc., Power Technology Inc., NUBURU Inc., L3Harris Technologies Inc., Coherent Corp., IPG Photonics Corporation, and Jenoptik AG. These companies represent the core of an ecosystem where vertical integration, partnership networks, and intellectual property play decisive roles.
Northrop Grumman and RTX have been instrumental in integrating semiconductor laser components into high-energy systems designed for counter-UAS and missile defense, often emphasizing thermal management and beam combining as key differentiators. Lockheed Martin continues to advance naval and ground-based directed energy platforms, utilizing diode laser technology as both pumps and direct emitters. nLIGHT has distinguished itself through high-power solutions, including contributions to Army DE M-SHORAD and coherent beam combining initiatives aimed at megawatt-class performance. Meanwhile, specialized players like Power Technology provide ruggedized diode modules for extreme environments, and NUBURU is pushing the boundaries of portable directed-energy platforms using high-power blue semiconductor lasers for counter-drone applications.
Recent developments illustrate the dynamism of this landscape. In early 2026, NUBURU completed a proof-of-concept for a portable directed-energy dazzler targeting counter-UAV defense, reinforcing the trend toward compact, deployable systems. That same month, BluGlass Limited entered a multi-phased development program with a U.S. tier-1 defense prime to create customized visible GaN DFB lasers and gain chips for dual-use applications, receiving an initial order as a signal of growing demand for specialized photonic components. Additionally, Power Technology updated its positioning to highlight high-performance diode modules suited for military defense in harsh operational settings. These moves, alongside earlier strategic alliances such as NUBURU network contract with Maddox Defense and Tekne S.p.A., highlight how partnerships and niche innovations are reshaping competitive dynamics.
The concentration of market share further emphasizes the importance of strategic differentiation. With a CR3 of 42.5 percent and a CR5 of 61.2 percent, the top firms command significant influence, but ample room remains for mid-tier and emerging players to carve out profitable niches through technology specialization, customization, or regional partnership strategies. Our report provides a detailed competitive mapping that allows stakeholders to assess competitor strengths, gaps, and potential vulnerabilities, enabling proactive positioning rather than reactive adaptation.
Industry Dynamics: Regulation, Supply Chains, and Innovation
The operating environment for semiconductor military lasers is heavily influenced by external forces that can accelerate or constrain market growth. Regulatory frameworks, raw material availability, and standardization efforts are among the most critical factors shaping strategic decision-making in 2026 and beyond.
Export controls represent a primary constraint. High-power semiconductor laser stacked arrays with specific wavelength and power parameters fall under dual-use restrictions defined by the Wassenaar Arrangement and U.S. EAR/ITAR frameworks. Compliance is not optional; it is a structural requirement for any organization participating in the global supply chain. Navigating these regulations demands a sophisticated understanding of classification, licensing, and end-use monitoring. Our research embeds these compliance considerations into the competitive analysis, helping firms evaluate how regulatory exposure may impact market access, partnership opportunities, and revenue potential in different jurisdictions.
Supply chain resilience is another pressing concern. Gallium, a critical material for fabricating high-power semiconductor lasers, is subject to geopolitical risks due to reliance on foreign sources and export restrictions. The National Defense Industrial Association analysis of directed energy weapon supply chains has highlighted these vulnerabilities, prompting defense programs to seek diversified sourcing and domestic production capabilities. For manufacturers and integrators, securing the supply of critical materials is as important as advancing the technology itself. The market study examines how material constraints intersect with demand growth, offering insights into potential bottlenecks and mitigation strategies.
On the demand side, the U.S. Department of Defense continues multi-year investments in directed energy programs, including scaling initiatives like HELSI that target 500kW to megawatt-class performance. Semiconductor lasers serve as foundational components, both as direct emitters and as pump sources for solid-state and fiber laser systems deployed in programs such as DE M-SHORAD and HELIOS. Furthermore, innovation pipelines are being sustained through government funding mechanisms such as SBIR and STTR topics, which support the development of bright blue semiconductor laser arrays and photonic crystal surface-emitting lasers for compact, high-brightness applications. These programs not only validate the strategic importance of semiconductor lasers but also create pathways for technology transfer and commercial scaling.
Standardization and integration challenges remain. The path to fielding megawatt-class systems involves overcoming hurdles in beam quality, thermal dissipation, and system reliability. Companies that can deliver modular, scalable components with proven performance in extreme conditions will be better positioned to capture long-term contracts. Our report integrates these dynamics into a cohesive framework, enabling stakeholders to assess how technological maturity, program funding, and regulatory shifts will interplay over the forecast period.
Operational Intelligence Within the Report
Beyond high-level trends, the Worldwide Semiconductor Military Laser Market study is designed as a decision-support tool that delivers actionable intelligence across multiple dimensions. The report structure enables users to drill into the components that matter most to their specific strategic needs, whether they are technology developers, system integrators, investors, or procurement advisors.
Key content areas include detailed market sizing with historical and forecast data, segmentation breakdowns that illuminate relative performance across regions, types, and applications, and competitive profiling that captures the strategic posture of leading firms. The study also examines recent corporate developments, partnerships, and program milestones that signal shifts in the competitive balance. In addition, the report contextualizes these findings within the broader regulatory and supply chain environment, providing a holistic view of the forces that could alter market trajectories.
For teams planning capacity expansion, technology roadmaps, or market entry, the segmentation and scenario information is particularly valuable. It allows for the identification of growth hotspots, the evaluation of regional demand patterns, and the assessment of how different application segments may evolve in response to threat landscapes and budgetary priorities. By combining quantitative projections with qualitative analysis of industry developments, the report equips users with the evidence base needed to justify investments, prioritize partnerships, and mitigate risk.
Worldwide Semiconductor Military Laser Market
The Strategic Imperative for 2026
The convergence of substantial market growth, intensifying competition, and complex external dynamics makes 2026 a pivotal year for organizations operating in the semiconductor military laser space. The revenue expansion projected through 2032 offers a compelling case for investment, but realizing value from that growth requires precise, up-to-date intelligence. Companies must understand not only the size of the opportunity but also where the value pools are forming, which technologies are gaining traction, how competitors are positioning themselves, and what regulatory or supply chain constraints could disrupt plans.
Our market research is built to answer these questions with rigor and clarity. It provides the depth and structure needed to transform raw data into strategic direction. Whether the goal is to secure a foothold in a high-growth segment, optimize a product portfolio for defense procurement cycles, or evaluate partnership and M&A opportunities, the report delivers the insights necessary to act with confidence.
Semiconductor Lasers Market
Stakeholders who rely on generalized industry narratives risk missing the nuances that separate high-performing strategies from suboptimal ones. Access to detailed segmentation, precise forecasts, and competitive intelligence is the difference between guessing and planning. PW Consulting Worldwide Semiconductor Military Laser Market study is designed to fill that gap, offering a single, authoritative source for the intelligence that drives informed decisions.
To fully leverage the insights outlined here and monitor the evolving dynamics of this critical market, readers are encouraged to consult the complete report. The full study contains the granular data, regional and application-level detail, and strategic analysis that are essential for shaping robust 2026 and beyond strategies in the worldwide semiconductor military laser market.
For detailed analysis of this topic, please visit the official page: Worldwide Semiconductor Military Laser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Phenolic Resin for Kraft Paper Market Worth $580.45M in 2025, Growing at 4.62% CAGR
By pmarketresearch, 2026-09-17
Phenolic Resin for Kraft Paper Production Market: Strategic Intelligence for 2026 Decision-Making
The global phenolic resin market for kraft paper production stands at a critical inflection point as we enter 2026. Between 2020 and 2025, the sector recorded revenue movements from approximately USD 465 million to USD 580 million, reflecting a compound trajectory shaped by evolving laminate demand, regulatory tightening, and raw material dynamics. Our newly released market research delivers the granular intelligence that executives, procurement leaders, and strategy teams need to navigate the forecast period from 2026 through 2032. This article previews the strategic architecture of the report, demonstrates the analytical rigor behind our findings, and outlines why this intelligence is indispensable for competitive positioning in the coming years.
Macro Trajectory and the 2026 Inflection Point
The market's historical arc from 2020 to 2025 reveals both resilience and structural volatility. Revenue climbed steadily through 2022, experienced a corrective contraction in 2023, and then resumed growth to close the historical window at USD 580.45 million in 2025. This pattern underscores a market that is sensitive to macroeconomic pressures yet anchored by non-discretionary industrial applications. Looking forward, our forecast model projects continued expansion through 2032, with 2026 expected to reach approximately USD 624.69 million and terminal-year revenue approaching USD 796 million. The forecast period CAGR stands at 4.62 percent, a rate that signals moderate but durable growth rather than speculative overheating.
For decision-makers in 2026, the key question is not whether the market is growing but where value will concentrate and which segments will outperform. The report dissects this trajectory through multiple analytical lenses—segment-level performance, regional supply-demand balance, and competitive intensity—without exposing the proprietary numerical breakdowns that form the core deliverable. What we can preview is that the growth narrative will be shaped by divergent regional industrial footprints, material-cost sensitivity, and the pace of regulatory compliance adoption across end-use sectors.
Segment Architecture and Application Dynamics
The research categorizes the market along three primary dimensions: resin type, geographic region, and end-use application. Each dimension carries distinct strategic implications for producers, converters, and downstream laminate manufacturers.
Resin Type Segmentation
The two dominant resin families—Resol-type and Novolac-type phenolic resins—serve different functional and processing requirements in kraft paper impregnation workflows. Resol variants are typically favored for applications demanding faster curing, superior cross-linking density, and enhanced moisture resistance, while Novolac systems offer cost efficiency and specific adhesion characteristics for certain laminate configurations. The report evaluates how each type's share of total market revenue reflects end-user technical specifications, regional manufacturing preferences, and the evolving cost-of-ownership calculations that procurement teams are making in response to phenol price fluctuations.
Application Coverage
Kraft paper impregnated with phenolic resin is deployed across a spectrum of laminate and composite applications. High-pressure laminates represent the largest application pool, driven by construction, furniture, and architectural surfaces where durability and chemical resistance are paramount. Decorative paper impregnation constitutes a significant secondary channel, supporting surfaces that balance aesthetics with performance. Industrial and technical laminates, along with plywood overlay and bonding applications, round out the demand base with specialized functional requirements. The study maps how application mix influences resin grade selection, processing parameters, and margin structures—and how these relationships are shifting as manufacturers optimize for both performance and compliance.
Regional Distribution
Geographic analysis in the report segments revenue across Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa. The distribution reflects divergent industrial ecosystems: Asia Pacific's scale advantages and manufacturing intensity contrast with Europe's emphasis on sustainability-aligned production and North America's regulatory-driven specification environment. The research does not merely allocate revenue shares; it examines the structural drivers behind regional performance, including local resin capacity, import dependence, downstream laminate fabrication density, and the impact of cross-border pricing differentials in phenol and formaldehyde feedstocks.
Competitive Landscape: Incumbents, Specialists, and Strategic Positioning
The phenolic resin for kraft paper production market is characterized by a mix of global resin specialists, regional manufacturers, and toll-production arrangements that together create a moderate concentration profile. Our analysis places the competitive environment in context using concentration metrics that indicate a market where leading players command meaningful share but do not exercise monopolistic control. This structure fosters both competition on technical performance and collaboration through toll-manufacturing and supply-chain partnerships.
Key Company Profiles and Strategic Roles
The report provides detailed company-level assessments of the principal participants shaping this market. Prefere Resins, headquartered in Germany, specializes in phenolic resins formulated for paper impregnation in industrial and decorative laminates, with a particular emphasis on kraft paper applications in high-pressure laminates where chemical resistance and machinability are critical. Metadynea Austria GmbH, based in Krems, produces phenolic resins used in kraft paper impregnation for laminates and wood composites, and has strengthened its sustainability positioning through certifications supporting bio-based raw material compliance. Bakelite, operating through its Hexion and Sumitomo Bakelite dimensions across the United States and Japan, supplies phenolic heat-reactive resins for saturating paper substrates including kraft paper, serving filtration, electrical, bearing, and gasket applications.
MÜNZING Chemie, located in Abstatt, Germany, complements the resin supply chain with additives that support phenolic resin-based industrial overlays and films for kraft paper in plywood and concrete forming applications, offering wetting agents and release agents that optimize PF resin impregnation. UCP Chemicals in Austria and Allnex Belgium both manufacture or offer phenolic resins targeted at kraft paper production for laminate and impregnation markets, reinforcing the European specialty-chemicals footprint. Capital Resin Corporation operates as a toll manufacturer in the United States, producing phenolic resins for industrial applications including paper impregnation and kraft paper composites. In Russia, PC Standart LLC produces phenolic paper consisting of specially impregnated kraft paper for plywood lamination and woodworking coatings, while Italy's Loma Srl manufactures LOMAPHEN-grade kraft papers impregnated with thermosetting phenolic resins for standard high-pressure laminates.
Recent Developments and Strategic Signals
The competitive dynamics are not static. Recent activity demonstrates how companies are adapting to shifting performance expectations and compliance requirements. In May 2025, Prefere Resins continued its supply of specialized phenolic impregnation resins for kraft paper in both high-pressure and low-pressure laminates, emphasizing improved surface characteristics and durability—an indication that surface quality and lifecycle performance are becoming differentiating factors. In December 2024, Metadynea Austria GmbH renewed its ISCC PLUS certificate for bio raw materials compliance, reinforcing its capability to supply sustainable phenolic resins for paper impregnation and signaling that bio-based feedstocks and certification-mediated market access are gaining strategic importance. In December 2025, MÜNZING Chemie referenced its FENTAK® additives portfolio for phenolic resin impregnation of core stock and industrial overlays on kraft paper-based films for plywood applications, illustrating how additive chemistry is being positioned to enhance process efficiency and end-product performance.
The full report expands these company profiles with competitive positioning analysis, supply-chain relationships, and an assessment of how each player's capabilities align with emerging application requirements. It also maps the implications of toll-manufacturing arrangements and regional production footprints for procurement flexibility and supply security.
Cost Structure, Raw Materials, and Pricing Realities
Any strategy for the phenolic resin for kraft paper production market must contend with the material cost foundation. Phenol accounts for approximately 50 to 60 percent of phenolic resin production costs, making phenol price volatility a direct determinant of resin economics for kraft paper impregnation. Pricing benchmarks from the third quarter of 2025 illustrate the geographic dispersion that manufacturers must manage: phenol-formaldehyde resin prices reached approximately USD 1,715 per metric ton in the United States, USD 1,370 per metric ton in China, and USD 1,695 per metric ton in Germany. This spread highlights the importance of regional sourcing strategies, logistics optimization, and hedging or contract structuring decisions that can materially affect margin outcomes.
The report integrates these raw-material dynamics into a broader cost-structure analysis that examines how resin producers and downstream converters respond to feedstock uncertainty. It considers the interplay between inventory management, regional procurement, and pricing pass-through mechanisms, providing a framework for evaluating cost resilience across different operating models. Rather than offering a static cost snapshot, the study constructs a decision-oriented view of how material-cost variability interacts with segment mix, regional positioning, and product-grade selection.
Phenolic Resin for Kraft Paper Production Market
Phenolic Resins Market
Regulatory Pressures and Compliance as Strategic Variables
Regulatory frameworks are increasingly shaping specification requirements and material choices in this market. In the United States, EPA TSCA Title VI formaldehyde emission standards govern composite wood products, and phenol-formaldehyde resins benefit from certain exemptions relative to urea-formaldehyde restrictions when used in hardboard and laminated products that meet threshold requirements ranging from 0.05 to 0.11 ppm depending on product type. For high-pressure laminates using phenolic-impregnated kraft paper, formaldehyde emission levels must typically remain below 0.05 ppm under E1 or equivalent classifications. These thresholds are not merely technical footnotes; they influence resin formulary decisions, process controls, and market access conditions, particularly for exporters and multinational laminate manufacturers.
The research places regulatory dynamics within the competitive and operational context, exploring how compliance requirements affect resin formulation priorities, certification pathways, and the relative attractiveness of different resin types and application channels. It also considers how sustainability certifications and bio-based feedstock credentials are becoming embedded in procurement criteria, extending the compliance conversation beyond emission thresholds to include lifecycle and sourcing considerations.
Forecast Outlook and Scenario-Based Planning for 2026–2032
The forecast window from 2026 to 2032 is the analytical centerpiece of the report. Building on the historical trajectory and current segment dynamics, the study projects revenue progression through 2032 and frames it within scenario-based considerations that help leadership teams stress-test their assumptions. Rather than presenting a single deterministic path, the report structures the outlook to accommodate variations in raw-material pricing, regional demand growth, regulatory adoption pace, and competitive intensity.
The forecast model reflects the market's 4.62 percent CAGR and incorporates the moderating influences of regional maturity and the accelerants of application-driven demand in construction, furniture, and industrial laminates. It also accounts for the potential impact of sustainability-driven substitutions, certification adoption, and shifts in the cost-of-ownership calculus as resin producers and converters adapt to material-cost volatility. By delivering this outlook within a structured analytical framework, the report enables readers to align their strategic planning with the most probable demand pathways while remaining prepared for alternative scenarios.
Report Contents and Operational Utility
This market research is designed as a decision-support tool rather than a general industry overview. It combines quantitative market sizing with qualitative competitive and operational analysis to provide a comprehensive view of the phenolic resin for kraft paper production landscape. The study includes:
- Detailed market size and forecast data spanning the historical period from 2020 to 2025 and the forecast window from 2026 to 2032, with revenue expressed in USD millions.
- Segment-level analysis by resin type, geographic region, and application, with interpretive commentary on the drivers behind each segment's performance.
- A competitive landscape assessment covering key companies, their headquarters and operational focus, and recent strategic developments that signal shifting priorities.
- Cost-structure and raw-material analysis that situates phenol price dynamics and regional pricing differentials within resin production economics.
- Regulatory and compliance context, including emission standards and sustainability certifications, mapped to their implications for resin selection and market access.
- Strategic recommendations and decision frameworks tailored for producers, converters, and downstream laminate manufacturers seeking to optimize positioning in a market characterized by moderate concentration and material-cost sensitivity.
The report is structured to allow readers to move quickly from macro trends to segment-specific insights and then to company-level intelligence, supporting both strategic planning and operational decision-making. By integrating quantitative data with interpretive analysis, it provides a foundation for evaluating investment priorities, procurement strategies, and competitive responses.
Why This Intelligence Matters for 2026 Decisions
As enterprises enter 2026, the phenolic resin for kraft paper production market presents a landscape in which growth is real but unevenly distributed, where raw-material volatility demands active cost management, and where regulatory and sustainability considerations are becoming embedded in specification and procurement decisions. In this environment, general market awareness is insufficient. What is needed is segment-aware intelligence that connects demand trajectories to resin types, regional supply conditions, competitive capabilities, and cost dynamics.
This report is built to supply that intelligence. It enables readers to identify where value is likely to concentrate over the forecast period, which application channels offer the strongest performance and margin potential, how regional dynamics influence sourcing and pricing strategy, and what competitive moves by key players mean for supply security and differentiation. By grounding the forecast in detailed segment and company analysis, it supports a range of decisions—from resin procurement and product formulation to capacity planning and market-entry evaluation.
The preview above outlines the scope and strategic logic of the research; the full study provides the underlying quantitative detail, segment-level breakdowns, and company-specific assessments that executives require to act with confidence. For organizations seeking to align their 2026 strategies with the realities of this market, the complete report offers the depth and precision necessary to convert insight into action.
For detailed analysis of this topic, please visit the official page: Phenolic Resin for Kraft Paper Production Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global AMC CPU Card Market to Reach $844.22M by 2032 Backed by 8.24% CAGR
By pmarketresearch, 2026-09-17
Strategic Intelligence for the Next Decade: Inside the Worldwide AMC CPU Card Market
The embedded computing landscape is undergoing a structural transformation. As industries converge around edge intelligence, 5G infrastructure, and mission-critical reliability, the Advanced Mezzanine Card (AMC) CPU segment has emerged as a critical enabler of next-generation system architectures. For executive teams navigating capital allocation, supply chain resilience, and technology roadmapping in 2026, understanding the trajectory of the Worldwide AMC CPU Card Market is no longer optional. It is a strategic imperative.
This article serves as a strategic preview of our latest market research initiative. It outlines the macro-level dynamics shaping the sector, highlights the competitive forces at play, and demonstrates why data-driven clarity in this space will directly influence enterprise decision-making through the end of the decade. The full intelligence package, complete with granular segmentation, regional revenue breakdowns, and forward-looking scenario modeling, is available through our comprehensive report.
The Macro Trajectory: Growth, Acceleration, and Structural Leverage
The market for AMC CPU cards has demonstrated consistent, compounding expansion over the past five years. Historical revenue data from 2020 through 2025 reveals a clear upward trajectory, with the sector surpassing the half-billion-dollar threshold in the base year and continuing to scale into the forecast horizon. Our analysis projects that this momentum will carry the market steadily toward higher valuation tiers through 2032, driven by entrenched demand in telecommunications, defense, and industrial automation.
The compound annual growth rate across the forecast period stands at a robust 8.24 percent, signaling that AMC-based processing architectures are not experiencing a cyclical spike but rather a structural adoption curve. This rate of expansion reflects the widening integration of MicroTCA and ATCA platforms across high-performance edge deployments, where thermal resilience, I/O flexibility, and processor density intersect. For organizations evaluating capacity planning or vendor partnerships, this macro outlook underscores the importance of aligning procurement strategies with a market that is scaling at a pace faster than general-purpose embedded compute segments.
Revenue projections through the end of the forecast window indicate that the market will continue to compound, with incremental year-over-year gains accelerating as next-generation processor architectures gain mainstream deployment in AMC form factors. The implication for enterprise strategists is clear: early positioning in supply agreements, standards-aligned procurement, and platform diversification will likely yield disproportionate competitive advantages as the market matures.
Architecture and Application: Where Value Is Concentrated
The segmentation landscape of the AMC CPU card market is defined by distinct architecture preferences and application-driven demand clusters. Processor architecture remains a foundational axis of differentiation, with x86-based modules commanding the largest share of market revenue, supported by established ecosystem maturity, extensive software compatibility, and broad availability of high-core-count processors. ARM-based architectures follow, reflecting the growing emphasis on power efficiency, edge AI inference, and specialized telecommunications workloads, while PowerPC architectures maintain a strategic presence in environments where long lifecycle support and deterministic processing remain paramount.
On the application side, demand is heavily weighted toward sectors that require ruggedized, high-availability computing fabric. Telecommunications continues to represent the largest application vertical, driven by the deployment of distributed baseband units, edge packet processing, and MicroTCA-based infrastructure modernization. Aerospace and defense follow as a critical adoption zone, where thermal tolerance, extended temperature operation, and compliance with stringent reliability standards make AMC CPU modules a preferred choice for mission systems and tactical communication platforms. Industrial automation and medical computing round out the demand landscape, with automation leveraging the modularity and backplane scalability of AMC architectures, and medical systems increasingly adopting compact, high-reliability compute nodes for imaging, patient monitoring, and diagnostic edge applications.
Regional distribution further illustrates the global nature of this market, with North America, Europe, and Asia Pacific each contributing substantial revenue streams. The balance across these regions reflects both mature adoption in established industrial and defense markets and accelerating deployment in Asia Pacific as manufacturing and telecom infrastructure investments expand. The global footprint of demand reinforces the need for multi-region supply chain strategies and localized technical support capabilities.
Competitive Landscape: Established Players and Innovation Velocity
The competitive environment in the AMC CPU card market is defined by a concentrated group of specialized manufacturers that have built deep expertise in MicroTCA and ATCA ecosystems. Market concentration metrics indicate that the top three players account for a notable share of total revenue, while the top five collectively represent a substantial majority of market activity. This concentration reflects the high barriers to entry associated with advanced backplane compliance, thermal design, processor integration, and long-term enterprise support commitments.
Kontron AG has maintained a strong position through its AdvancedMC processor modules, including the AM4010 and AM4022 series, which bring Intel Core processor performance, ECC memory support, and high I/O density to telecom, industrial, and defense applications. VadaTech has similarly expanded its Processor AMC portfolio, offering single- and double-width variants based on Intel Core and Xeon architectures, with a clear emphasis on PCIe, Ethernet, and storage flexibility for MicroTCA environments. Recent product activity from VadaTech, including the introduction of 11th Generation Intel Core i7-based modules with quad-core performance up to 4.4 GHz turbo and the continued expansion of its MicroTCA product line, signals an ongoing commitment to performance upgrades and form-factor versatility.
Worldwide AMC CPU Card Market
N.A.T. Europe has carved out a distinct niche through versatile AMC CPU boards that span both ARM-based and COM Express-enabled designs, such as the NAT-AMC-LX2 with 16-core ARM A72 processors and the NAT-AMC-COMex supporting COM Express Type 7 modules with high-bandwidth backplane connectivity. This dual-architecture approach positions the company to serve deployment scenarios that require either power-efficient ARM processing or Intel-based ecosystem compatibility. EMCOMO Solutions AG has pursued a similarly broad strategy, supplying MicroTCA AMC CPU modules built around Intel Xeon E3, Xeon E5, and Xeon D processors, alongside NXP QorIQ and Cavium-based options, with features including NVMe support, 10GbE connectivity, and industrial temperature ranges. Advantech Corp. rounds out the competitive field with embedded computing solutions that include AMC-compatible modules and network mezzanine cards, targeting industrial, telecom, and edge applications with systems that support high-core Intel Xeon processors.
The competitive dynamics in this space are not solely defined by product portfolios. They are increasingly shaped by the speed at which manufacturers can align with updated standards, integrate next-generation processor families, and maintain supply continuity amid broader semiconductor capacity constraints. Organizations evaluating vendor partnerships must therefore assess not just current module availability, but also roadmap alignment, compliance certification depth, and long-term support commitments.
Industry Dynamics and Supply-Side Pressures
The operational environment for AMC CPU card deployment is being reshaped by several intersecting forces. One of the most consequential developments is the ratification of the MicroTCA.0 Revision 3.0 specification, which introduces 100 GbE and PCIe Gen 5 fabrics, delivering a fourfold performance improvement while expanding thermal design power limits to accommodate higher-performance processors. This standards evolution directly enables more aggressive compute deployments within the same AMC form factor, broadening the addressable use cases for edge and server-adjacent applications and supporting up to 12 slots in demanding configurations.
At the same time, supply-side dynamics are introducing new layers of complexity. TSMC expansion has triggered shortages and price surges for certain filter materials used in wafer manufacturing processes critical to advanced semiconductor production, creating upstream constraints that ripple through CPU and component availability. Concurrently, major processor manufacturers are boosting CPU production capacities amid strong demand, yet lead times for certain CPUs have extended to as long as one year, with pricing continuing to escalate. These supply pressures elevate the strategic importance of forward purchasing, alternative architecture evaluation, and multi-sourcing strategies for organizations that depend on AMC CPU modules for critical deployments.
For enterprise decision-makers, these dynamics create a dual challenge: maintaining performance and reliability targets while managing cost volatility and lead-time uncertainty. The ability to anticipate standards-aligned upgrades, secure supply commitments, and evaluate architecture alternatives will differentiate organizations that can sustain deployment timelines from those that face costly delays.
Inside the Research: What Decision-Makers Will Find
Our Worldwide AMC CPU Card Market research is designed to translate these macro dynamics, competitive forces, and supply-side pressures into actionable intelligence. The report provides a structured, data-rich view of the market across multiple analytical dimensions, enabling teams to evaluate growth opportunities, assess competitive positioning, and align procurement and technology strategies with a rapidly evolving landscape.
The research package includes detailed historical and forecast revenue analysis spanning the full 2020 to 2032 window, offering a clear view of how the market has evolved and where it is headed. Segmentation analysis breaks down revenue and growth trajectories across processor architecture families and application verticals, allowing readers to identify which domains are driving expansion and where demand intensity is expected to intensify. Regional breakdowns provide a global perspective on market distribution, supporting supply chain mapping and geographic prioritization.
Beyond quantitative segmentation, the report delivers a competitive landscape assessment that profiles key manufacturers, outlines their product strategies, and contextualizes recent product launches, standard ratification impacts, and supply chain developments. This section is designed to help organizations benchmark vendor offerings, evaluate roadmap alignment, and understand the strategic implications of recent industry events. The research also incorporates an analysis of market concentration dynamics, highlighting how competitive balance, barriers to entry, and standards evolution are shaping the trajectory of the sector.
Motherboard Market
Operational relevance is a core design principle of the report. Rather than presenting abstract market statistics, the analysis is structured to support concrete decision-making processes, including vendor selection, capacity planning, architecture evaluation, and risk assessment in the face of semiconductor supply constraints. The goal is to provide executive and technical teams with a shared, evidence-based foundation for strategic planning.
Why 2026 Is a Pivotal Year for Strategic Positioning
The convergence of standards modernization, processor architecture evolution, and supply-side volatility makes 2026 a defining year for organizations operating in or adjacent to the AMC CPU card market. MicroTCA.0 Revision 3.0 is opening the door to higher-performance deployments within established form factors, while demand from telecommunications, aerospace and defense, industrial automation, and medical computing continues to expand the addressable market. At the same time, lead-time extensions and material-driven cost pressures are testing the resilience of procurement and deployment strategies.
In this environment, strategic clarity is a competitive asset. Organizations that understand the relative growth intensity of different architectures and applications, that can anticipate the implications of standards evolution, and that have visibility into competitive dynamics and supply constraints will be better positioned to make informed decisions about platform investments, vendor relationships, and deployment roadmaps. The market's projected expansion through 2032 reinforces the long-term nature of this opportunity and the importance of getting strategic positioning right early.
This preview provides a high-level view of the forces shaping the Worldwide AMC CPU Card Market and the strategic value embedded in comprehensive market intelligence. The full research report delivers the detailed segmentation, regional revenue distributions, competitive assessments, and forward-looking analysis needed to translate these insights into concrete action. For teams seeking to navigate the market with precision and confidence in 2026 and beyond, the complete intelligence package offers the depth and structure required to support decisive, evidence-based strategy.
For detailed analysis of this topic, please visit the official page: Worldwide AMC CPU Card Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com